Author: sunline

  • Sunline Listed in Two Impactful Industry Rankings in China

    Sunline Listed in Two Impactful Industry Rankings in China

    Recently, Sunline has been listed in two impactful industry ranking, “2020 China Top 100 Competitive Fintech” and “2020 Forbes China 50 Most Innovative Companies”, reaffirming Sunline’s ability in continuous innovation and achievements.

    The President of China, Xi Jinping has always urge companies own their key technologies, ensuring they always stay up to date with the latest. Sunline always ensure the company is heavily invested in key technologies such as application development platforms, DevOps, distributed, microservices, and enterprise-level financial open platforms, leading the industry with technology advancement.


    Sunline is ranked in 2020 China Top 100 Competitive Fintech

    On June 29, Zhongguancun Internet Finance Institute and China Internet Finance Forum (CIF30) released the list for ” China Top 100 Competitive Fintech”. Sunline has made it to the list with its strong competitiveness in various sub-sectors of financial technology, high capital market recognition and industry representative strength.


    The winners were strictly selected in terms of growth, leading in terms of models and technologies, technology-intensive, innovation-driven and can support national strategies or drive new formats.

    In terms of technological innovation, it has long embedded in to Sunline’s genetic. The story of Sunline’s establishment began in 2002 with the hope to build a platform to allow talented and motivated individuals to make use of their talents to truly realize the common growth of themselves and the company. For the past 18 years, Sunline has been adhering to the spirit of continuous innovation and gradually becoming the nation’s first-class financial technology company.


    Sunline makes it to 2020 Forbes China 50 Most Innovative Companies

    On June 22, Forbes China announced “2020 Forbes China 50 Most Innovative Companies”, with leading enterprises like Huawei, Alibaba Cloud, Sunline and other companies in the industry successfully making it on the list.


    Forbes evaluates the nominee’s innovation ability in terms of business model, enterprise R&D investment, core independent intellectual property rights, transformation of scientific and technological achievements as well as the growth of the company to rank. A total of 50 local enterprises have been nominated. Forbes China hopes to pass the list Identify companies that lead the development of the industry or have a significant influence on the progress of the industry.
    For the past 18 years, Sunline has focus in providing the best financial technology and innovation for the industry through continuous research and development. In 2019, Sunline has invested 15% of the company’s revenue in research and development, technical personnel in the company accounted for more than 90% of the total employees and has received nearly 300 software copyrights. Besides being the first service provider in China to develop the industry’s first JAVA based core banking system, Sunline is also the first to develop distributed core banking system, the first to develop a distributed, microservice and unified based core banking system as well as many first in the industry.


    Sunline continuously walk the path of innovation that empowers the development of the industry with technology and enhances China’s financial industry with the best technologies. Sunline will continue to lead the development of the financial industry in the nation and promotes the ambition of China’s financial technology to lead the development of financial technologies in the rest of the world.

  • CB Insights Gives Three Reasons for Ranking Sunline as China’s Top 50 Fintech

    CB Insights Gives Three Reasons for Ranking Sunline as China’s Top 50 Fintech

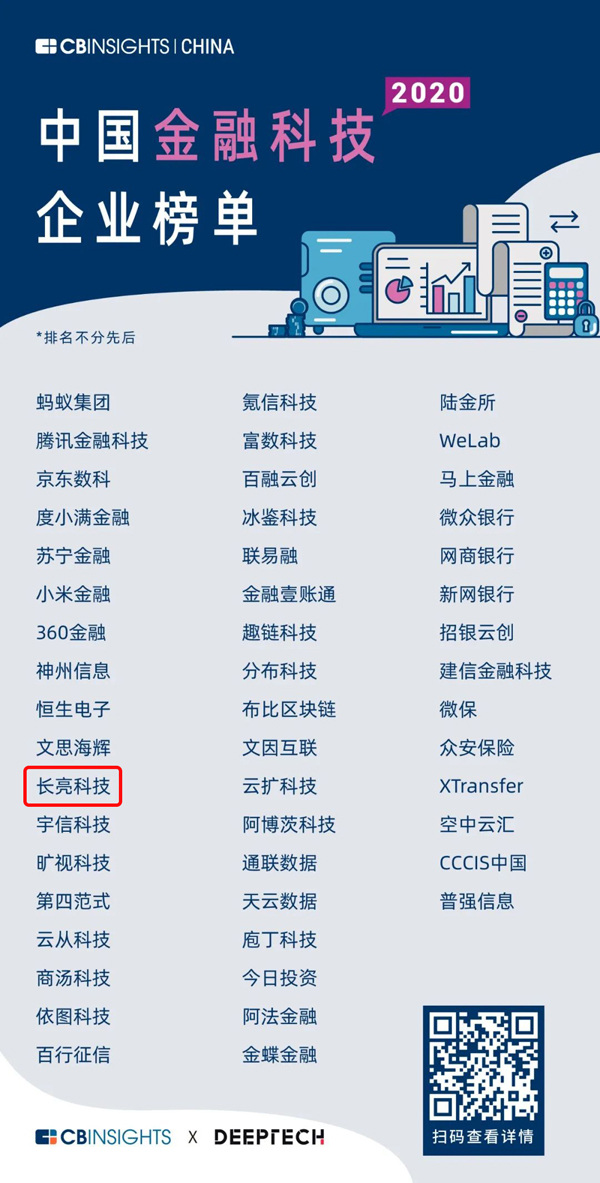
    On June 29, CB Insights China announced CB Insights China’s Top 50 Fintech List and Sunline has made it to the list with the company’s technological advantages, market development and overall impact on the financial industry.

    CB Insights China ranks top Fintechs according to their breakthrough innovative technologies and excellent business models. Based on the DPTC system (Depth, Popularity, Tendency, Collaboration), CB Insights comprehensively evaluates the Fintechs’ strength, external attitudes, trends and cooperation performance, then selects the top players in China’s Fintech among the nominees.

    In the field of china’s financial technology, Sunline has become synonymous as a strong fintech innovator, having their own proprietary technologies in key areas and has been leading the development of the financial industry by empowering the digital transformation and core modernization initiatives of financial institutions.


    CB Insights View:

    CB Insights China comprehensively evaluates the reasons for Sunline to be selected as Top 50 Chinese Fintech companies:

    Sunline focuses mainly on the development and implementation of core banking systems, being one of the few companies in China to have a completely independent core system:

    •   In 2019, Sunline created a new-generation core business system based on the domestic financial-grade distributed database Tencent TDSQL for Zhangjiagang Rural Commercial Bank, helping the bank become the first commercial bank in the country to have a domestic distributed core business system.

    •   The main position of Sunline’s previous business was small and medium-sized commercial banks. In 2019, Sunline won the bid for China Postal Savings Bank and achieved a steady market expansion to the large state-owned commercial bank market.

    Sunline is quite competitive in the field of financial big data analysis. In addition to winning the bid for Bank of China’s payment system data governance consulting service project in 2019, the company also joined the Huawei Intelligent Data Alliance to target the Big Data Industry and jointly build the big data ecosystem with upstream and downstream partners.

    In terms of overseas expansion, Sunline focuses on the Southeast Asian market. In 2019, its overseas business scale exceeded 100 million revenue for the first time and achieved profitability. It became the first company to successfully land a Chinese core solutions in a large-scale Southeast Asian bank.

    (The above content is from the CB Insights perspective)

    Making it to three consecutive impactful rankings in the industry not only represent the high degree of recognition by industry authorities but also a strong proof of Sunline’s outstanding comprehensive capabilities and independent innovation capabilities in the financial technology field. Sunline will continue to empower the development of the industry with innovative technological methods and business models, aiming to be the top global financial technology provider.

  • Sunline Explores Opportunities of Open Banking with Three Core Capabilities

    Sunline Explores Opportunities of Open Banking with Three Core Capabilities

    The exploration of data sharing and open data in banking has contributed to the development of open banks in UK and EU. In China, a number of large domestic banks such as Bank of China, China Merchants Bank, Shanghai Pudong Development Bank have launched their own open platform. Sunline have a deep understanding in the development and business essence of open bank, taking the lead in building an open financial platform and enabling banks to grasp the opportunities of open banking.

    Open banking is an integral part of the digital transformation path of commercial banks, emphasizing on customer-centricity, Open API, SDK to deepen partnership between bank and third party businesses through the integration of financial services and lifestyle scenarios to enhance optimal allocation of financial resources and services efficiency, achieving a win-win for both the bank and its partners. Open Banking Ecosystem uses Banking-as-a-service (BAAS) as a medium to connect bank and technology partners, enabling bank to leverage the innovative capabilities of partners for the provide lifestyle scenario services while partners can leverage the data from banks to provide customers with customized financial services that meet their needs.

    The bank opening up its finances becomes inevitable

    Banks’ operating system always siloed and the IT department of the banks often have to face lengthy timeline in project delivery hence product innovation to meet the constant demand changes of customers are also affected. With an open banking business model, banks can improve their services and provide better user experience.

    The urgency of open banking in small and medium-sized banks is greater than large banks because:

    • The capital cost and customer acquisition cost of large banks are much lower than that of small and medium-sized banks. Large banks have strong financial strength and their competitive advantages will become more and more obvious.

    • Small and medium-sized banks are at a disadvantage in the competition with large banks but they can partner with third party vendors on scenarios they lack, allowing the banks to focus on financial services that they excel in, enhancing the overall competitiveness of banks.

    Sunline Helps Banks Seize Opportunities with Open Banking Opportunities Through Leading Open API Technology

    Sunline’s is one of the pioneer in open banking has helped develop numerous mature and stable solutions for banks and financial institutions of different sizes. Sunline’s financial open platform is a technology platform that implements data sharing around open API technology, providing security control, open portals, API lifecycle management, operation and maintenance monitoring, sandboxing, process orchestration as well as other functions designed to help banks enrich financial scenarios and enhance financial services. As of 2019, Sunline has implemented open platform for financial institutions such as Ping An Bank, Bank of Dongguan, Bank of Zhengzhou, Bank of Dalian, Jifu Group and others.

    Advanced architecture enables banks to get more with less

    • Sunline’s Open Platform integrates financial capabilities with lifestyle scenarios and enhance financial capacity to the scene party through the open domain.

    • Scene domain: The partner uses open API to implement various user scenarios.

    • Open domain: Open domain includes the API (SDK tool) to provide user authorized access and API gateway (used for routing and forwarding, access control, etc.) to the scene domain.

    • Shared domain: Provides common services to open platforms and services through process orchestration.

    • Open portal: Provides an entrance for API display retrieval and provides a standard process for partner access.

    • Integrated operation management: Includes portal website management, access process management, operation monitoring management, API gateway management, etc.

    • Application domain: Back-end financial applications that provide financial services.

    The core competence of The Open Platform of Evergreen Technology Finance

    1.  API Gateway as the core domain

    The key technology of open banking is API and the key technology of open platform is API gateway. Open APIs can be divided into three categories which are open internal APIs, open APIs to partners and open external APIs. As the entry of these three types of API calls needs to go through the API gateway, it is most appropriate for the API gateway to carry out the access control and authentication of different APIs.

    The core functions of the API gateway are:

    • Routing and forwarding.

    • Message conversion and parameter mapping.

    • Multi-protocol access to the gateway supports http(s), rpc, dubbo, webservice, tcp and protocol scalability.

    • API governance functions including parameter check, fuse degradation, limit flow, grayscale routing, concurrent control, time-out control, etc.

    • Security controls such as IP black-and-white list, SSL/TLS, JWT certification, OAuth2 certification, etc.

    Gateways, as the entry point for traffic require transaction-level logs and link tracking, log management, and monitor alerts. The API gateway has evolved into a feature-rich, external component that can provide services independently.

    2.  Open portal and integrated transport for a complete access process

    Although the core domain of the gateway is completed, the API services of the open platform can communicate and reach agreement with partners through offline methods, but there are many problems associated with offline communication.

    For banks:

    • There is no platform for unified management and release of APIs because the entire lifecycle management of the API depends on manual offline services.

    • There is no unified platform for access partner management because the access process relies on offline communication.

    • There is no authentication process for APIs consumed by partners.

    For partners:

    • Partners do not have a unified API search portal for the APIs opened by the bank.

    • There is no standard access procedure for APIs provided by consumers.

    By opening the portal, partners can access the complete access procedures, API display and promotion, help documents, enterprise certification, sandbox experience, developer center, call monitoring and other functions.

    3.  Open service

    Open services are public services provided by open platforms to business parties. These services are gradually evolved by banks during the opening process and play a very important role in the opening process of APIs. Existing open services include global pipeline services, billing services, authentication services, process orchestration services, etc.

    Process orchestration services

    Process orchestration service is a core capability of the open platform. It can quickly connect or combine services in the industry to meet changing scene-side requirements. The open platform can achieve capability reuse through process orchestration. Internal services are orchestrated and exported via API (internal orchestration can span all-row business systems), and external requests can call corresponding API interfaces after passing authorization authentication.

    Take the opening of an account to activate a ball game as an example, through the process of orchestration services, the combination of the API interface of the digital account opening of the account center, the marketing center’s marketing activity compliance inspection interface and the third-party API interface of the ticketing platform are the three services that jointly achieve account opening and delivery Scene of ball game tickets.

    Through the process orchestration service and services can be combined. The necessary verification and data mapping are added to provide an external combined service to the scenario.

    Billing services

    Billing service is an essential part of the bank’s implementation of API economy and the billing service can be billed according to the billing rules set by the bank, such as the number of calls implemented.

    • The gateway is the unified entrance for API calls and the API gateway pushes the call pipeline information to MQ.

    • The billing module pulls pipeline information from MQ and stores it in the database. The daily scheduled task counts the total number of calls on T-1 day according to the application and API dimensions and saves it into the library.

    Certified Licensing Services

    Banks’ financial services must be exposed on the public network and security must be considered. Here, the security of the entire transaction is guaranteed by means of authentication and authorization and signing and encryption.

    Open platform docking microservices framework

    Open platform uses a microservice architecture system. During the implementation process, if the open platform is to interface with many microservices, there will inevitably be problems that must be solved under the microservice architecture including service dependency management, service governance, full stack level monitoring, call link analysis, log management, etc.

    In order to solve the problems inherent in the microservices framework, the open platform is connected to Sunline’s microservices framework platform to obtain a full range of operation monitoring at the application service level, including application and component monitoring alarms, log analysis, link tracking, application component as well as performance monitoring and analysis.

    A future-proof open banking platform cannot be achieved without the guidance and regulation of supervision as well as the support and drive of cutting-edge technologies such as artificial intelligence, big data and cloud computing. In the exploration and practice of open banking, Sunline’s Open Banking team has accumulated rich experience and API usage scenarios and has continuously improve the technical framework of its financial open platform, verifying the advanced concepts and mature capabilities. Sunline’s Open Banking team will continue to strengthen technological innovation to help banks seize the development opportunities of open banks and promote the development of open banks in China.

  • Here Comes the Nation’s First Distributed Microservices Built Core Banking System

    Here Comes the Nation’s First Distributed Microservices Built Core Banking System

    6th June 2020 marks the official operation of Sunline’s new generation distributed V8 core banking system in Bank of Dongguan. The advanced technology and outstanding support ability to the business will empower core modernization initiatives and realize digital transformations for banks.


    Core banking system should actively empower digital innovations of banks

    Core banking system is the core competence of Sunline ever since the development of the company. For the past 20 years, Sunline has led the transformation of core areas of numerous banks through continuous innovation of its core banking system and has maintained one of most preferred technology partners for banks.

    The next generation core banking system should have customer-centric business processing ability with unified and microservices based architecture in order to meet the requirements of massive data and transaction processing in the digital era. The architecture needs to be able to support the flexible combination of service level deployment and unify unlimited dynamic expansion to meet the scalability needs of banks in their future business development, have the abilities in development, business and technology agility to support rapid innovation of financial products. A future-proof foundation of the core system is crucial in empowering a bank’s digital transformation and innovation.

    With almost two decades of experience in financial technology and business, Sunline has integrated the finest architecture in the development of the newly launched SunLTTS V8 system. As the nation’s first core banking system with a unified microservices based architecture, SunLTTS V8 will help banks solve performance bottlenecks, improve high availability and dynamic capacity and quickly realize digital transformation with flexible products, pricing and marketing.


    SunLTTS V8 – The nation’s first distributed microservices based unified architecture

    The distributed architecture can be divided into several modes:

    1.  Microservices architecture that is split according to business modules, such as: deposits, loans, etc.

    2.  Unit-based structure according to customer dimension, slicing of core data scattered to multiple database management

    3. Microservices based unified architecture not only simplifies the complexity of the system but also boost horizontal expansion ability and is the industry-leading distributed architecture model

    Sunline combined advanced financial technologies and experience to develop an enterprise-class distributed microservices based unified core banking system to effectively improve the availability and scalability the bank’s system, boosting cost-effectiveness and efficiency of the bank.


    Microservices:

    V8 adopts microservices based architecture at the application level and is based on domain modeling theory which decouples the bank’s core business system according to the business area, dividing it into functional groups such as customer center microservice group, product center microservice group, public microservice group, deposit microservice group, loan microservice group, accounting microservice group, each microservice group which consist of a series of single functional responsibilities and high cohesive business services.


    Celling:

    V8 uses a distributed solution based on the unified architecture design pattern, partitioning the data by customer dimension. Each partitioning as one unit with its own unique application and data. For example, a bank with 100 million accounts is divided into 10 units, hence each unit store and manage 10 million accounts. The subsequent dynamic scale-out of the unit will effectively cope with the massive data and transaction processing requirements of the big data era.


    Why is V8 better and is leading the industry?

    The new generation distributed V8 core business system gives the bank more vitality, actively empowering the digital innovation of the bank.


    Practical architecture:

    V8 microservices architecture fully reflects the software engineering for “strong cohesion low coupling” design concept and can effectively reduce the complexity of the system, construction, upgrade, operation and maintenance risk, bringing greater convenience to the development and application of the system.


    Flexible deployment:

    V8 adopts microservices architecture to give the system a strong degree of flexibility, dynamically adjustable access mode between services, enabling the system to be flexibly assembled into a variety of deployment architecture, including micro-service group deployment mode, united deployment mode, micro-service group and uniting combination of deployment, centralized deployment, etc. to meet the deployment needs of different levels of banks;


    Easy expansion:

    The microservices architecture model allows each services to scale independently and deploys the scale of the needs based on the size of each service. The modular architecture provides great convenience for the overall expansion of the system by rapidly building a complete business-completed logical deployment unit. At the same time, the distribution of large amounts of business data evenly to the different machine nodes of the database cluster allow the bank to better meet the processing requirements of account and transaction billion severity.


    Secure operating system:

    Each node in application layer of the system adopts cluster deployment and the data layer avoids single point of failure by defining a clear service boundary between subsystems. The united architecture can effectively isolate failures through units, narrow the “explosion radius” and avoid having an impact on the total number of customers.


    Faster development and operation:

    V8 version has a complete set of development operations tools, using Sunline’s independently developed microservices framework (SunEDSP) and application development platform (SunADP) to support the integrated operation management suite (MOne platform) and deep integration of DevOps system, effectively solving the bank’s core business system with distributed micro-services application development, continuous delivery, continuous integration, containerization and cloud deployment. Based on the service gateway, the system can flexibly adapt a variety of protocols with traffic control, packet routing, fail-over, failure recovery, service fuse, service degradation, permission control, security control, parameter filtering and other service governance capabilities.


    More comprehensive business functions:

    V8 adopts customer-centric, product-based and data-driven business function design based on componentized technology solutions to build a business processing center for different scenarios of banks. V8 not only has a perfect multi-legal system entity, flexible transaction and accounting separation mechanism, comprehensive financial product factory, multi-modal account system, but also supports personalized differential pricing, online and offline scene integration processing, fully demonstrated the customer-centric full-service capabilities, while being able to speed up the digital transformation process of banks, enhance open capacity, build a financial services ecosystem to provide a strong trading engine.


    Sunline has always been a leader in Core Banking System

    Sunline has almost two decades of experience in the development of core baking systems, possessing leading proprietary technical capabilities in distributed technology components as well as strong business and technical capabilities, and. As early as 2015, WeBank joined forces with Sunline to build the first domestic financial localized distributed core banking system with unit-based architecture, and which Sunline has successfully implemented for Bank of Shanghai, Zhangjiagang Rural Commercial Bank, Jingu Rural Commercial Bank, Huatong Bank and other banks. During the outbreak, Sunline core business system team is still actively engaged in the implementation of the large state-owned bank under construction, Dongguan Bank and other distributed core business system projects, and as June 6 has successfully helped put into operation Dongguan Bank’s new generation of distributed core banking system.

    With a deep understanding in the banking industry and implementation experience, coupled with the innovative gene and holding to independent research and development to continuously enhance the core business system capabilities to support the development of banks, Sunline is known as the leader of financial technology innovation. At present, Sunline has served nearly 100 banks in their core modernization journey.
  • Sunline Selected as the Sole Partner in Shanghai Pudong Finance’s New Business System Transformation Project

    Sunline Selected as the Sole Partner in Shanghai Pudong Finance’s New Business System Transformation Project

    Recently, Sunline successfully helped Shanghai Pudong Development Group Finance Co., Ltd. (Shanghai Pudong Finance) launch the new generation financial business system and create an industry benchmark project in the field.


    As the “internal bank” of an enterprise, group finance company takes on increasingly important functions of capital management and financial services. However, with financial globalization and rapid advancement of digital technology, group finance companies are facing strong competitions from other financial institutions and fintechs. Transforming with the right technologies and remaining at the top of the competition has become a major issue that group financial companies must solve.


    Shanghai Pudong Finance takes advantage of the trend, driving business transformation with digital technology

    Shanghai Pudong Finance is one of the first batch of financial companies established in Shanghai and is first-class in terms of innovation. Serving as the “heart” of the business operations of the group finance company as well as supporting the management information system and decision support system. Hence, having a highly flexible, secure and scalable business system is the key step for the digital transformation of Shanghai Pudong Finance.


    Shanghai Pudong Finance’s traditional business system can no longer meet the needs of both internal and external environmental changes, and is unable to support the continuous development and management of the company.

        ·  Tight coupling causing high degree of reliance between system modules

        ·  Low degree of automation and slow realization of business cycle

        ·  Collection, analysis and use of data unable to meet demands

        ·  Lack of flexibility in approval processes

        ·  Aged equipment with insufficient safety measures


    Shanghai Pudong Finance is in urgent need of a new generation digital business system to drive organizational model optimization, business model innovation, business process and user experience improvement.


    Sunline’s new generation business system empowers the digital transformation of Shanghai Pudong Finance

    The business system developed for Shanghai Pudong Finance covers all main businesses such as core, settlement, credit, digital banking, traditional banking, investment, interbank and reporting systems. The requirements for software service providers are very strict and was based on a comprehensive evaluation of the vendor’s professionalism, security and service capabilities. Sunline was selected as Shanghai Pudong Finance’s sole partner in the company digital transformation project after careful inspection and comparison at various levels.


    September 2018 marked the official commencement of the project. Although there were a large number of systems involved, complexity of the business being extremely high and the delivery timeline was tight, delivering the highest quality solutions represents Sunline’s professionalism. Sunline’s project team devoted almost a year developing the system and on 1st October 2019, Shanghai Pudong Finance’s trial system with core, settlement, credit, banking and online banking modules was successfully launched. On 1st January 2020, the investment, interbank and reporting systems were successfully launched. Sunline’s project team not only won the praise of Shanghai Pudong Finance but also achieved became more professional, responsible, mature and confident.


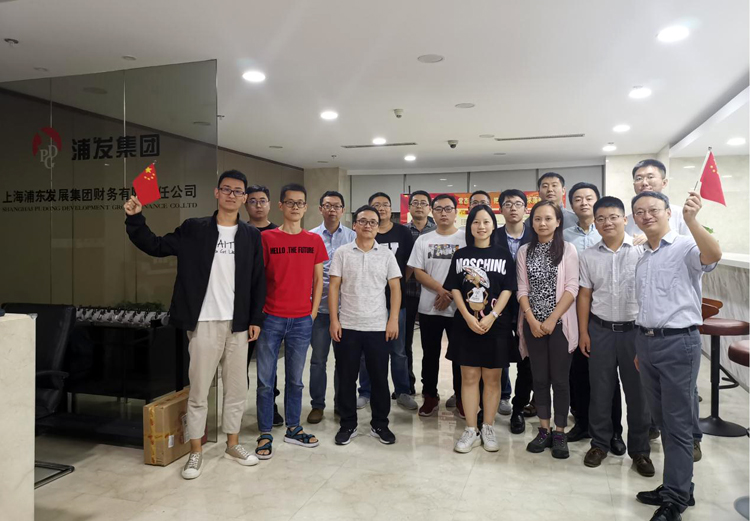
    Picture with customers after successful launch of trial system on 1st October 2019


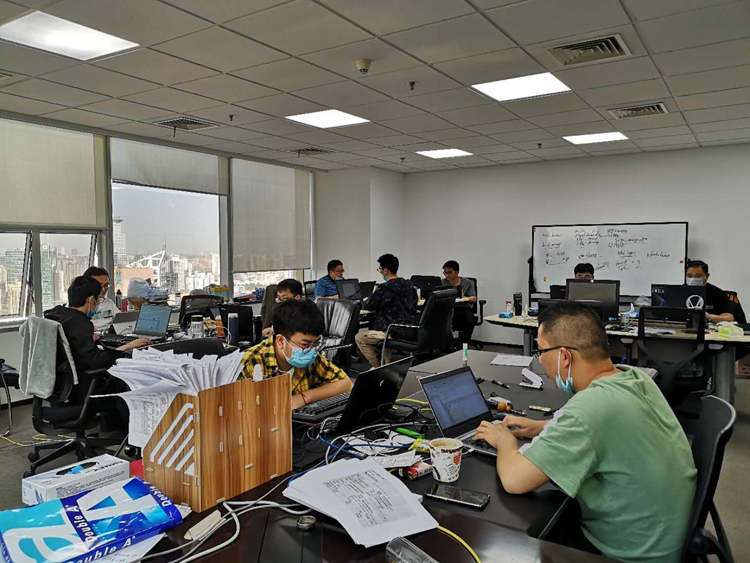
    Data reconciliation by project team


    With the joint efforts of Sunline and Shanghai Pudong Finance, the financial business system was officially launched on 1st May 2020. For this project, the system has run stably without bugs affecting business operations and various online indicators has exceeded expectations, receiving unanimous praises from IT and business departments of Shanghai Pudong Finance.


    Shanghai Pudong Finance’s next-generation business system significantly improves the company’s business capabilities, overall strength and competitiveness:

        ·  Realize the process, standardization and information of internal management

        ·  Achieve a full range of centralized fund management

        ·  Realize service personalization and improve the overall user experience

        ·  Realize intelligent supervision and decision-making of leaders


    To fully meet the needs of the business transformation and development of Shanghai Pudong Finance, enabling Shanghai Pudong Finance to better its economic function as a financial services company.


    The successful launch of Shanghai Pudong Finance’s new generation business system will have a strong demonstration effect and influence on the whole industry. As the sole partner in the reformation of Shanghai Pudong Finance’s business system, Sunline’s innovative technologies and professional services to enable Shanghai Pudong financial new trend of business development, accelerate the transformation of science and technology to productivity, to provide best practices for the transformation of financial company business systems.


    As the sole partner in the reformation initiative of the entire business system of Shanghai Pudong Finance, Sunline has employed innovative technologies and professional services to empower the business development of Shanghai Pudong Finance. With this project, Sunline can provide best practices in the transformation of business systems for group finance companies.

  • Sunline Heightens the Development of Bank of Shanghai’s Loan Business

    Sunline Heightens the Development of Bank of Shanghai’s Loan Business

    The recent winning of the core banking project for Postal Savings Bank has once again reinstated Sunline’s foothold in the field of core banking system. This article will share in details the advanced nature of the core system for loan business.


    The rapid development of digital finance and the nation’s support for small and medium-sized enterprises in the recent years have ushered the transformation of banks towards ‘big retail’ and a robust, flexible and scalable system with comprehensive transaction and accounting functions has become increasingly prominent in supporting the development of banks’ loan businesses.


    Sunline customized a novel loan business system for Bank of Shanghai

    In order to implement the development towards ‘boutique banking’ and ‘big retail’ strategies, Bank of Shanghai needed to enrich the credit financing business and improve speed to market but the bank’s traditional loan system was slapped with limitations like inflexible technical structure, inability to support the online transaction 24×7, inability to support multiple loan models, failure to support credit card repayment methods and incapability to meet the accounting method of discount loans. In order to meet the transformation objectives for Bank of Shanghai’s loan business, the loan core system must be able to support the accounting needs of diverse scenarios, various loan businesses and the different accounting needs for digital loans and traditional personal loans. As a leader in the loan businesses online and offline, Bank of Shanghai hopes to set up an ecosystem with Sunline’s core as the center of the loan business system.


    Sunline, with more than a decade of experiences in the research, development and implementation of core banking system in the industry has develop a set of advanced, mature and robust loan business system that highlights the concept of ‘one product, versatile functions’. Sunline Loan System provides agile customization according to the specific needs of bank loan business, enabling banks to quickly build loan products as well as to avoid business risks in a market with serious homogeneity, and has been widely used in leading retail banks.


    The new retail loan system developed by Sunline for the Bank of Shanghai adopts distributed architecture to realize application distribution at the business application layer, adopts a unitized architecture so that each unit has its own database and uses the three elements of the customer for the latitude of the data division to realize as array of credit products and credit services quickly as well as to provide support for the rapid access of both online and offline credit business scenarios.


    Advanced underlying architecture as the foundation of change in business functions

    Advanced Framework:

    ·  The technology architecture of the loan system is divided into access layer, control layer, data layer and infrastructure layer to realize functions like service access, transaction control, transaction routing as well as online and batch platform support

    ·   The overall architecture achieves effective separation of data, business components and transactions through layering, realizing separation of business data and business logic

    ·   Provide development platform functions such as integrated development, version management, metadata management and continuous delivery

    ·   Provide efficient operation platforms such as monitoring, logging, management, and configuration link tracking

    ·   Provide basic support platforms such as registration center, message center, cache center, etc.


    Advanced technology:

    ·   Adopts microservices technology architecture to realize object-oriented high cohesion and low coupling

    ·   Adopts DevOps processes to shorten the development cycle, ensure quality and agile production

    ·   Fully supports distributed deployment and scalability by building a complete business logical deployment unit

    ·   Separation of transaction and accounting, support 24×7 transaction, reconciliation mechanism between systems and application of active/active architecture design


    Underlying Functions:

    ·   The system can provide an array of credit products and services to meet the rapid development of banks on the digital era

    ·   Support traditional private-to-public loans, mortgage loans, digital loans, trade finance and derivative advances, joint loans, syndicated loans, entrusted loans, committed loans as well as other loan products

    ·   Multiple interest calculation methods, multiple accrual frequencies and multiple settlement payment methods

    ·   Support asset securitization, asset transfer and other asset businesses

    ·   The interest rate of each loan can be set according to the needs


    Sunline has developed loan system for companies like Bank of Shanghai and car loan  system for Fortune Auto Finance, Yueda Auto, Brilliance Auto and other car loan businesses which have been launched while projects for Jizhi Auto Loan, People’s Bank of China Ningbo Branch, Gold Mantis and other micro loan businesses are in production and will be live soon.

  • Another Breakthrough in Consumer Finance Market With The Winning of BOC Consumer Finance Project

    Another Breakthrough in Consumer Finance Market With The Winning of BOC Consumer Finance Project

    Recently, Sunline sees another breakthrough in the consumer finance market, winning the bid for the new generation consumer finance platform project for BOC Consumer Finance to transform the organization into a digital native.


    Sunline empowers the transformation of BOCCF

    BOC Consumer Finance (BOCCF) is one of the nation’s first consumer finance companies established with the approval of the China Banking Regulatory Commission and is operating comprehensively under the Bank of China. In the era of internet consumer finance that comes with the trend of interest rate liberalization and financial disintermediation, Fintechs have begun setting foot in the credit and financing businesses. In order remain competitive and future-proof in the era where digital and internet prevails, BOCCF will undergo transformation, starting with the development of a new generation consumer finance system.


    As one of the leaders in the consumer finance industry, BOCCF’s transformation has a very strong demonstration effect for the entire industry. With 6 months of continuous research, analysis, consultation planning and testing to produce a scientific rigor, Sunline’s new generation consumer finance system has been highly recognized by BOCCF for its technological advancement and performance superiority to help the organization efficiently realize its 3 main strategic goals, ‘finance + inclusion’, ‘finance + scenarios’ and ‘finance + technology’.


    Innovative concepts combined with hard core technologies creates leading solutions

    The new generation system for BOCCF comprises of the core of the system and other core functions including approval process, post loan and risk control management as well as transaction-level large ledger which are directly related to the business quality and efficiency of BOCCF. A comprehensive system with capabilities in digital financial, big data and background management services will ensure exceptional user experience, risk control, performance evaluation and business decision analysis.


    With more than a decade of knowledge in the end-to-end business of financial institutions and the experiences in the evolution of the financial industry, Sunline has applied them in the development of BOCCF’s new generation consumer financial system platform, helping the organization provide customers with good user experiences, risk control and security related technical support. With big data analytics, the system realizes strengthened real-time analysis, decision-making capabilities as well as eKYC to provide flexible and efficient product services as well as support the rapid development of future online and offline consumer finance businesses, empowering BOCCF to lead a new round of financial development strategy and realizing the organization’s transformation path towards “digital, scenario-based and intelligence”.


    Sunline’s new generation consumer finance platform is designed with the security, stability and controllability in mind. Incorporating the characteristics of internet and digital to support massive users, transactions and data, covering a wider range of businesses and realizing flexible applications to the everchanging market demand.


    The platform adopts micro-service and distributed architecture. Application splitting microservices, asynchronous decoupling of message queues, read and write separation reduces database IO pressure, cache peaking and data distribution, laying a solid technical foundation for the development needs of BOCCF.


    Sunline digital finance business highlights its strong competitiveness in the industry

    Based on the company’s latest annual report, Sunline’s digital finance businesses has maintained a strong growth. Under the influence of the ‘Internet+’ trend, Sunline has launched its digital banking system with WeBank, the nation’s first digital bank in 2014 and became the first company in the industry to propose and implement the digital transformation solutions for commercial banks. With continuous improvements and upgrades, Sunline’s digital banking solution has been widely implemented in the nation’s large commercial banks and financial institutions like Postal Savings Bank, Ping An Banks, Industrial Bank, Hengfeng Bank, Zhejiang Rural Credit Union, Anhui Rural Credit Union, Jilin Rural Credit Union, as well as overseas commercial banks  in Malaysia, Thailand and Indonesia. In 2015, the cooperation with Baidu Financial has opened doors for Sunline in the consumer finance market.


    The collaboration with BOCCF not only mark Sunline’s first entrance into the large state-owned consumer finance market, also represents Sunline’s subsequent expansion into the consumer financial market.

  • Why Is Sunline IBS Financial Control Platform So Outstanding?

    Why Is Sunline IBS Financial Control Platform So Outstanding?

    What is Sunline IBS Financial Control Platform?


    A one-stop comprehensive business system that resolves financial management’s issues on marketing management, mixed operation, diversified financial services and all-round supervisions. The system focuses on business operation, resource management and financial service capability output characteristics for financial control platforms. It not only enables the management of the entire operation of the financial unit but also realizing centralized customer management, perfect accounting system, flexible financial products and pricing model, unified accounting engine as well as a full range of supports for management requirements and business development innovation.


    Sunline continuously empowers the capabilities of the financial industry

    In the critical period of economic restructuring in China, traditional industries and the emerging industries urgently needed diversified financial services. Business innovation, comprehensive supervision and social financial services also showed a diversified trend. This is how financial model of multi-level capital market and the whole industry chain came into being, with financial platform becoming a major trend. In order to meet the diversification and expansion needs of financial institutions, the performance of financial control platform’s own integrated business system becomes crucial. It needs to fully support the financial development and innovation needs of the financial control platform.


    In order to meet the needs for continuous financial business development and innovation as well as to improve overall resources control and collaboration capabilities of a financial control platform, Sunline developed a hierarchical, customizable and highly reusable integrated business system used in various mainstream financial control platforms.


    Sunline IBS Financial Control Platform empowers TCL Financials’ one-stop financial services

    Integrating characteristics of TCL’s one-stop financial services, Sunline Financial Control Platform for TCL provided a unified financial account management system with centralized financial product management and account processing as well as flexible pricing system. Comprehensive coverage of TCL’s product supply chain provides effective support for the development and innovation of various financial businesses of TCL Financial.


    Sunline IBS Financial Control Platform fully meets the multi-level needs of Hisense Finance

    Sunline has built a comprehensive integrated business system that focuses on the various core business, accounting, analysis and management needs for the financial control platform for Hisense Finance. Not only can it support a multi-organizational structure to meet the needs of the continuous expansion and development of system, it also supports the maintenance of new business varieties. Through flexible parameter configuration, the need to add on new businesses can be realized, enabling Hisense Finance to achieve financial services support, improving the efficiency of business processes and realizing paperless offices.


    Sunline is very strict in developing high-quality innovative products and solutions

    The comprehensive Sunline IBS Financial Control Platform focuses on focuses on business operation, resource management and financial service capability output characteristics for financial control platforms. The accounting system, flexible financial products and pricing models as well as a unified accounting and calculation engine fully support the management requirements and business development innovation of the financial control platform.


    Advanced business framework: Sunline IBS Financial Control Platform can be divided into five platforms: business operations, financial core, unified settlement, risk control and technical support which will realize business management of the front, middle and back offices, transaction processing and risk management, enablement of responses for each sub-business at the front desk as well as centralized accounting of large-scale operations in the middle and back office that will significantly reduce the workload and pressure of staffs and improve business processing efficiency.


    Advanced technologies: The system is built on distributed, microservices, cloud native and other technologically advanced architectures as well as open and loose coupling designs to achieve architecture-level security, stability, flexibility and efficiency. The system supports clustered and high reliability applications, enables workflow development platform to quickly customize business processes and standardize UI development as well as allow quick function customization with task-driven business process mode.


    Advanced design concept: Based on the concept of ‘small core, large peripheral’, the system offers a customer-centric financial business model which supports a flexible accounting system, interest rate and rate marketization, meets the regulatory multi-dimensional reporting requirements and provides support for future differentiated customer marketing.


    With the gradual reformation of China’s state-owned enterprises, innovation and expansion of financial services were further promoted. Business units continued to increase and the comprehensive financial business system presents obvious advantages in providing diversified and comprehensive services.


    Sunline is as a leading financial solutions provider with not only has a deep understanding in the evolution of financial technologies, but also teams with rich project implementation experiences. With their duty to empower the development of the financial control platform as a driving force, Sunline continuously reinventing its solutions by integrating latest technology trends with industry best practices to provide comprehensive and secure financial solutions.

  • Sunline Attains the Core Banking Project for Postal Savings Bank of China

    Sunline Attains the Core Banking Project for Postal Savings Bank of China

    Sunline welcomes yet another historical moment for its core banking business, striking the first win with a state-owned bank. This project sees Sunline empowering Postal Savings Bank of China in the modernization the bank’s core banking system and remittance modules, transforming the bank with innovation and technology.


    Sunline helps Postal Savings Bank of China build the first ever state-owned domestic core banking system benchmark

    Postal Savings Bank of China (PSBC) is a leading large state-owned commercial bank with more than one billion accounts and nearly 40,000 outlets, serving more than 600 million individual customers. In response to the rapid changes in the banking sector in the era of digital banking and to counter the increasingly fierce competitions from Fintechs and Challenger Banks alike, PSBC decides to ride the wave of digital transformation and deploy an enterprise architecture based core banking system that is built on open platform and micro-services architecture. The transformation not only improves the efficiency and quality of PSBC’s products and services but also realizing the reactivity to provide customer-centric products and services. The PSBC’s new core banking project is the first project where a large state-owned bank adopts a unitary service model in the core system.

    The new generation technology platform implemented by Sunline is the most important technical underlying architecture of the core banking system. It is the most fundamental platform that will directly determine the ability of the core banking system to support the bank’s business development. The technology platform in PSBC’s project adopts the most advanced distributed and microservices architecture, allowing each unit to work independently with autonomy. The flexibility of microservices lets the system expand fast to support the massive transactions and data, comprehensively sustaining PSBC’s business transformation needs with advanced technical architecture.

    Sunline also implemented enterprise modeling and standardized analysis process for PSBC’s remittance business to evaluate the performances and optimized the internal and external flows, making the business more efficient and effective.


    Historical breakthrough for Sunline – Marching into Large State-owned Banks Market

    State-owned banks are gradually entering into core modernization. With information security and technology control becoming a national strategy, PSBC is taking the lead in launching a new generation core banking system transformation, successfully starting the localization and upgrading of the core banking system of large state-owned banks. This will further catalyze the comprehensive and profound digital transformations of other large state-owned banks.

    Sunline started its core banking business in 2002 and has since served more than 700 customers. The company began serving urban commercial banks and rural commercial banks, and moved into joint-stock banks with Ping An Bank and Shanghai Pudong Development Bank projects. The constant development of the banking industry and Sunline’s commitment in continuous innovation has made the company an industry leader. The win in PSBC’s core banking project successfully opened the door for Sunline to set foot into the market of large state-owned banks, gaining first-mover advantage and competitive advantage for the company.


    Sunline is the Leader in Localized Core Banking System

    As the leading banking software and technology services company, Sunline is committed in providing the best self-developed technologies and solutions for the financial industry in China. The company has successfully implemented distributed core banking systems for banks like Bank of China (BOC), Huatong Bank, Bank of Dongguan, Jingu Rural Commercial Bank as well as BOC’s owned virtual bank in Hong Kong, providing them with abilities to handle billion-level users and transactions. The system is designed based on a distributed architecture which can deliver requests and responses between services loosely and deploying all applications to be customer-centric, fully demonstrating Sunline’s leading technical capabilities in distributed technology.

    The cooperation with the PSBC is the first domestic benchmark core banking system project for a large state-owned bank, which plays a decisive role and a great milestone for the banking industry of China, PSBC and Sunline.

    Sunline is known in the industry as the “second technology arm of financial institutions” with deep understanding of banking business, rich implementation experience and active innovation genes. The market share and winning rate of the Sunline’s self-developed core banking system have always maintained a leading position, cumulatively provided core banking system implementations for nearly 100 banks. Working with PSBC is the most powerful affirmation of Sunline’s strength and industry position in the bank’s core system field. The ability to help PSBC successfully transform created a perfect industry benchmark.

  • Why Has Cashless Usage Upsurged in Times of Covid-19 Outbreak?

    Why Has Cashless Usage Upsurged in Times of Covid-19 Outbreak?

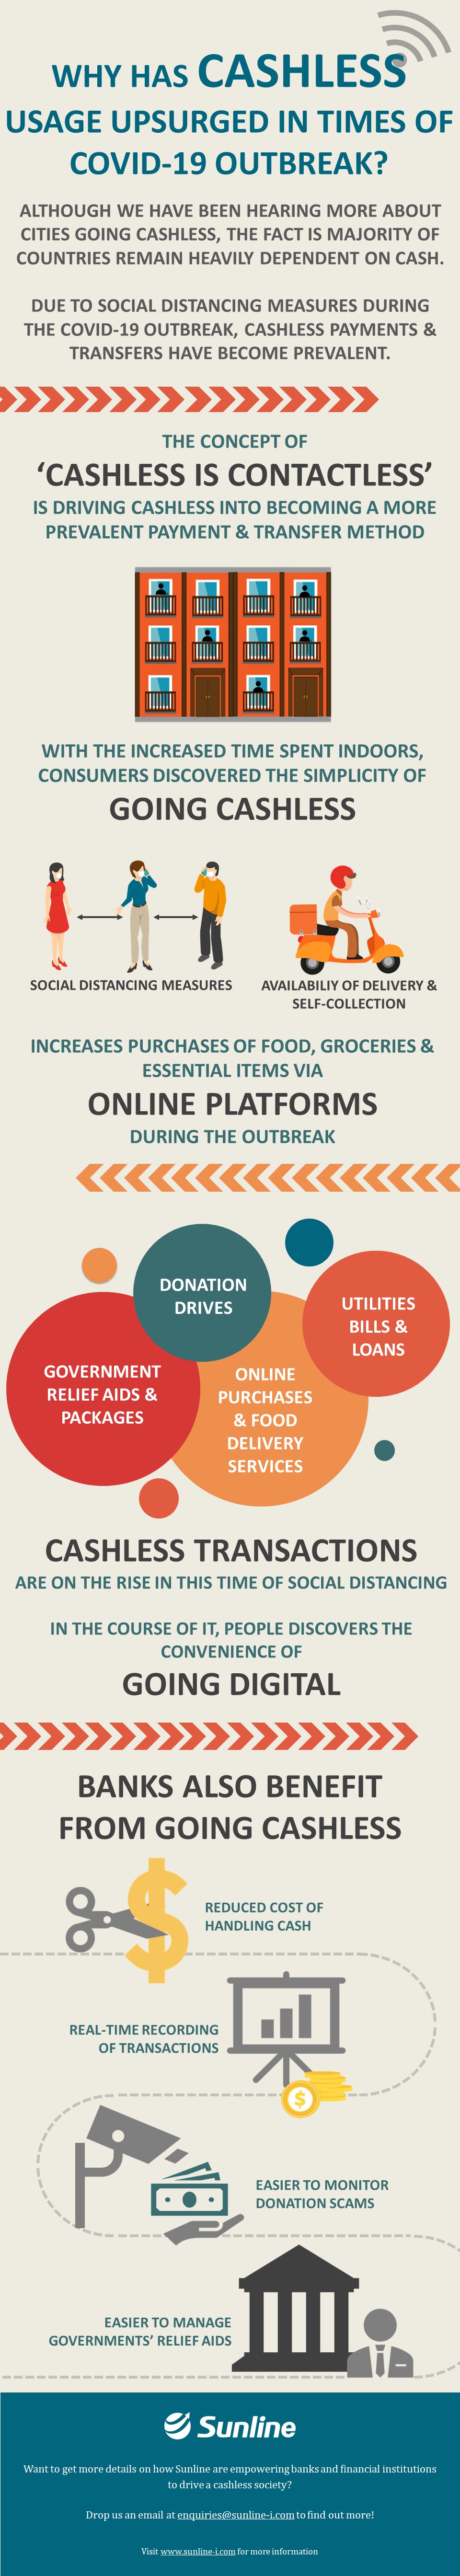
    Although we have been hearing more about cities going cashless, the fact is majority of countries remain heavily dependent on cash.


    Social distancing measures and the concept of “cashless is contactless” drove cashless payments & transfers to become prevalent during the covid-19 outbreak.