Category: News

  • Beyond the Intelligent Core: Sunline Advances Agentic Banking Architecture at HUAWEI CONNECT 2026

    Beyond the Intelligent Core: Sunline Advances Agentic Banking Architecture at HUAWEI CONNECT 2026

    SHANGHAI, September 18, 2026 – At HUAWEI CONNECT 2026 in Shanghai, Sunline takes banking intelligence beyond the transaction core, focusing on how core modernization, intelligent applications and AI-powered engineering are beginning to converge as banks move into the Agentic era. The direction reflects a broader shift in banking technology, where modernizing the core is increasingly connected with how banks use data, deploy AI and evolve complex technology environments.


    This convergence is reflected in Sunline’s Agentic Banking Architecture, which connects capabilities across the banking technology stack, from transaction processing and data intelligence to AI-driven applications and software engineering.


    From Core Banking Modernization to Agentic Banking

    The architecture is structured around three mutually reinforcing capabilities: Modern Core, Agent Core and AI Engineering. Together, they connect trusted transaction processing with real-time intelligence, AI-driven action and technology evolution.


    Modern Core, powered by SunCBS and APStack, provides the cloud-native transaction foundation for mission-critical banking. Agent Core, built around DataMind, DStack and AIS, connects banking data with enterprise AI and agent orchestration to support intelligent applications across business, operations and technology. AI Engineering, supported by SunTCR and AI-assisted engineering capabilities, applies intelligence to code understanding, knowledge generation and software engineering, helping development teams understand complex systems and deliver change more efficiently.

    Together, the three capabilities form a continuous intelligence loop: Transact, Understand, Act and Evolve, connecting banking operations with the intelligence and engineering capabilities required for continuous modernization.
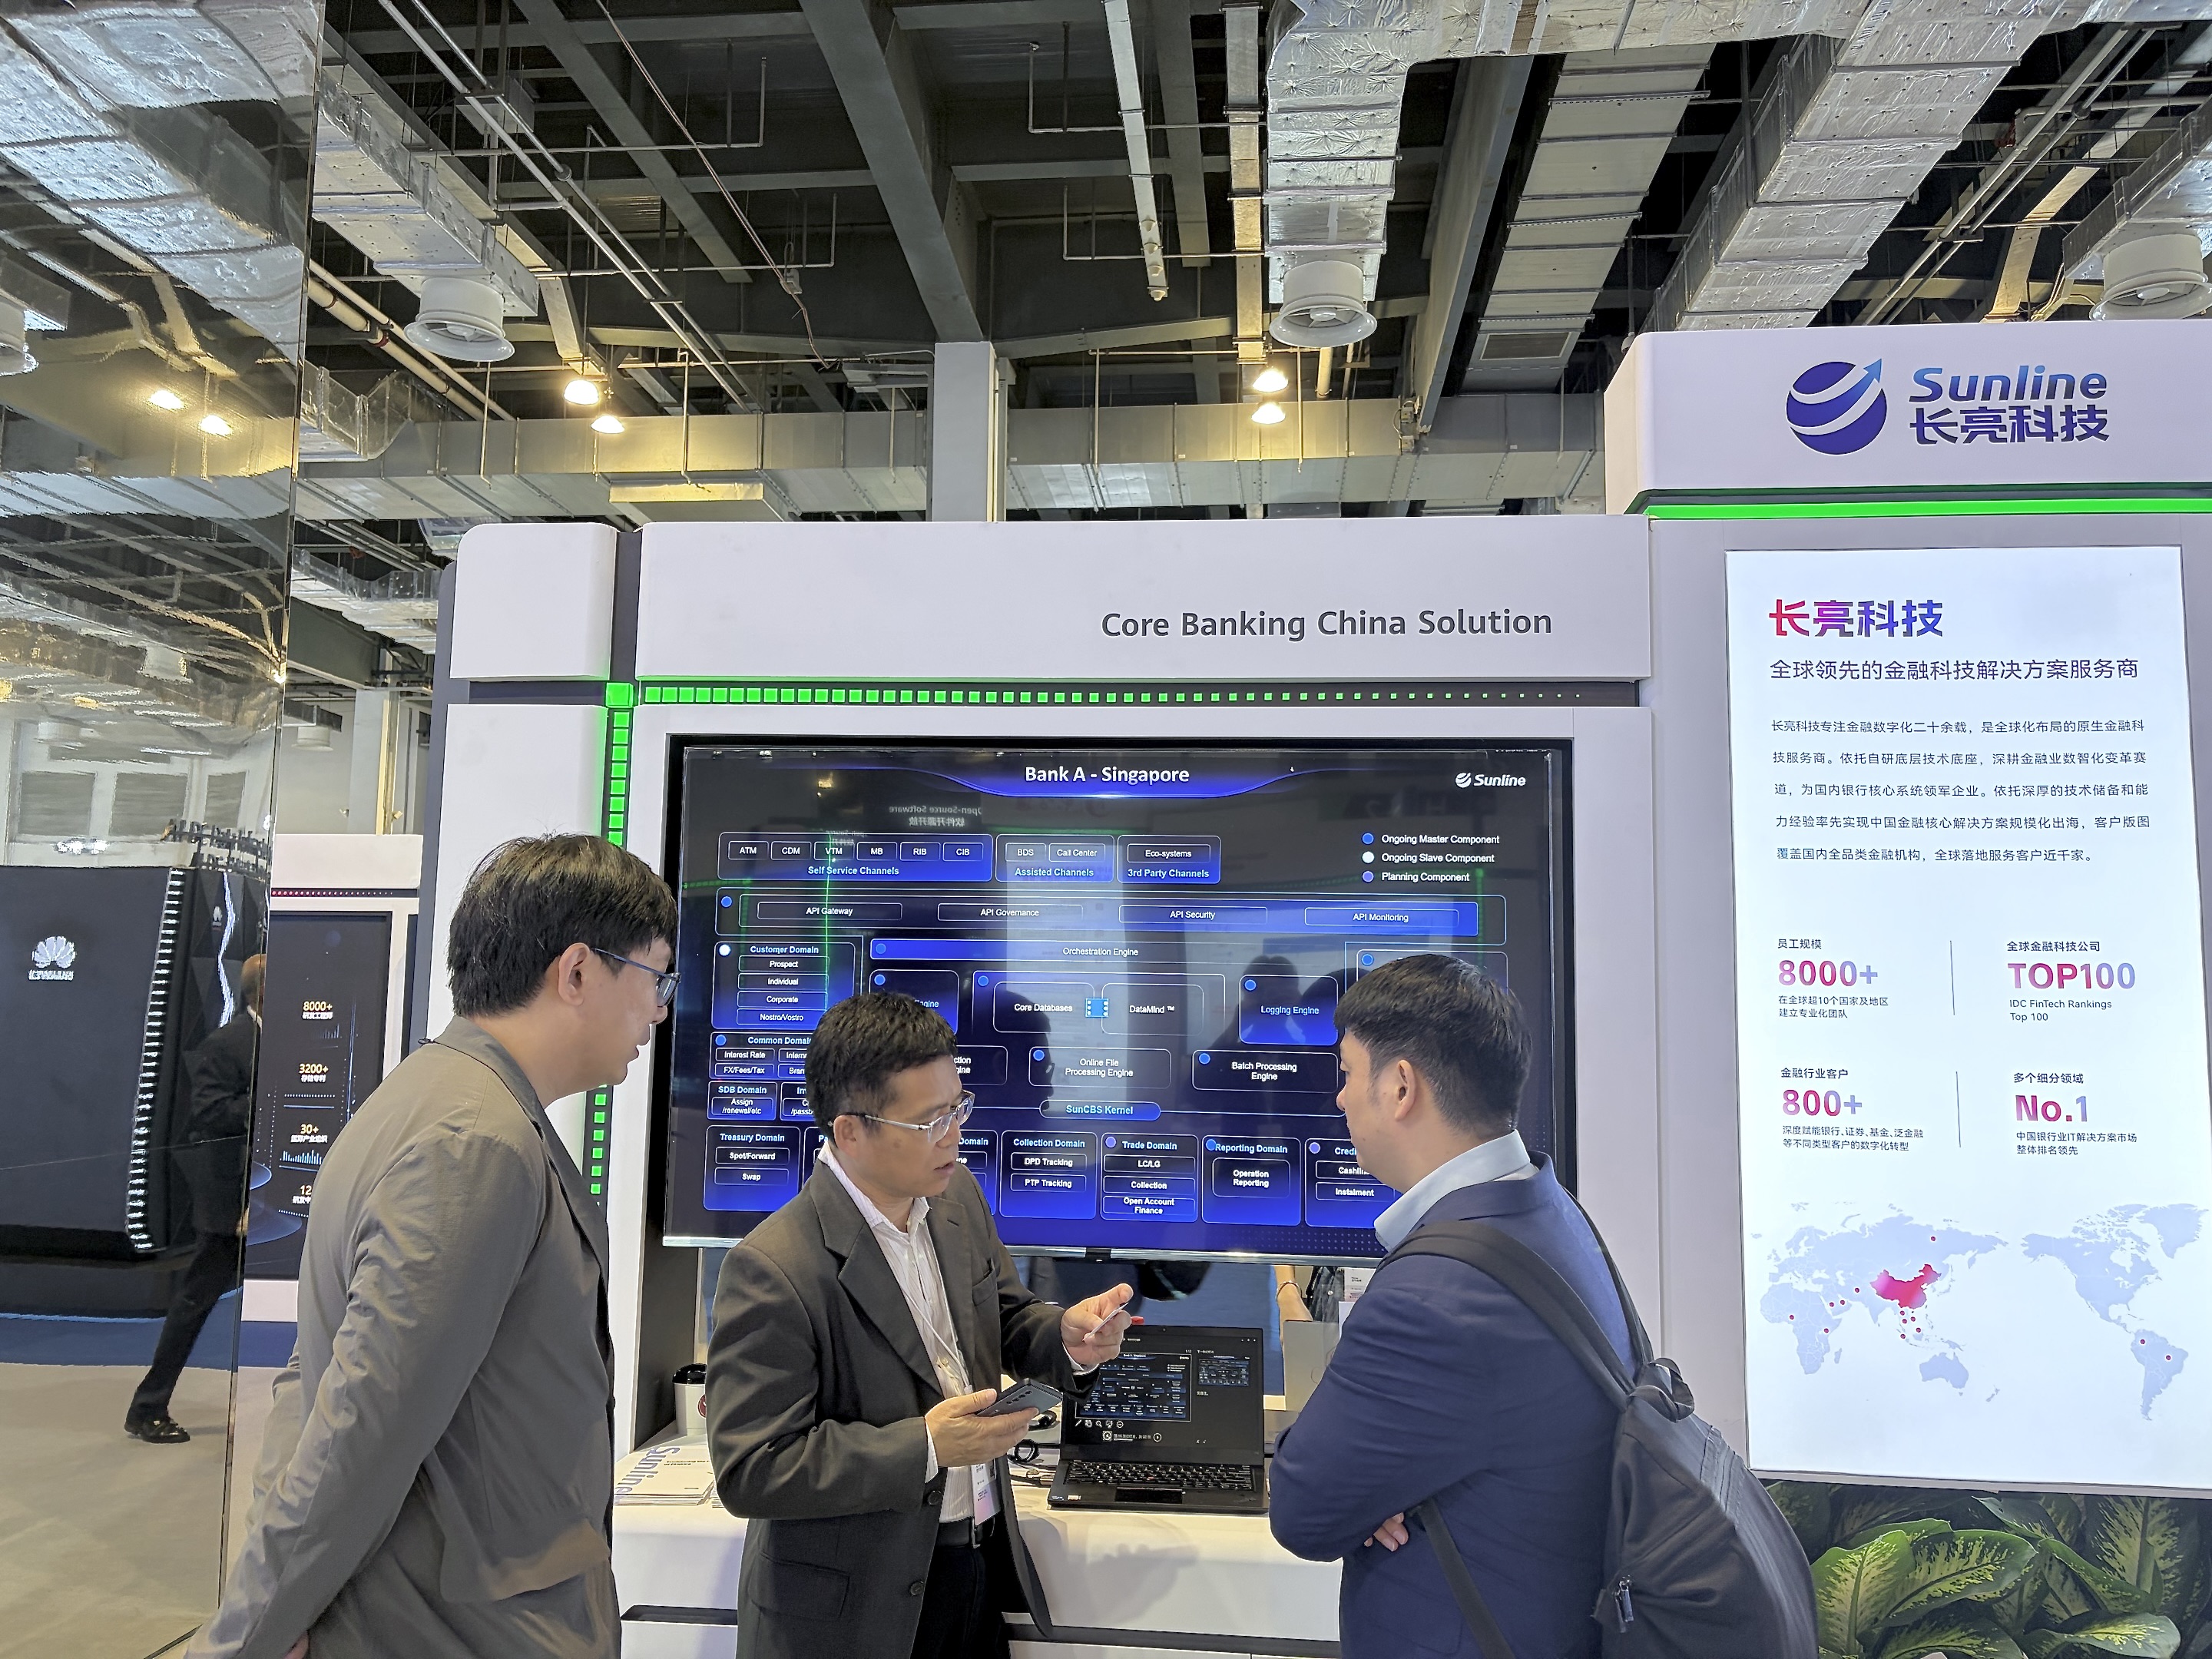

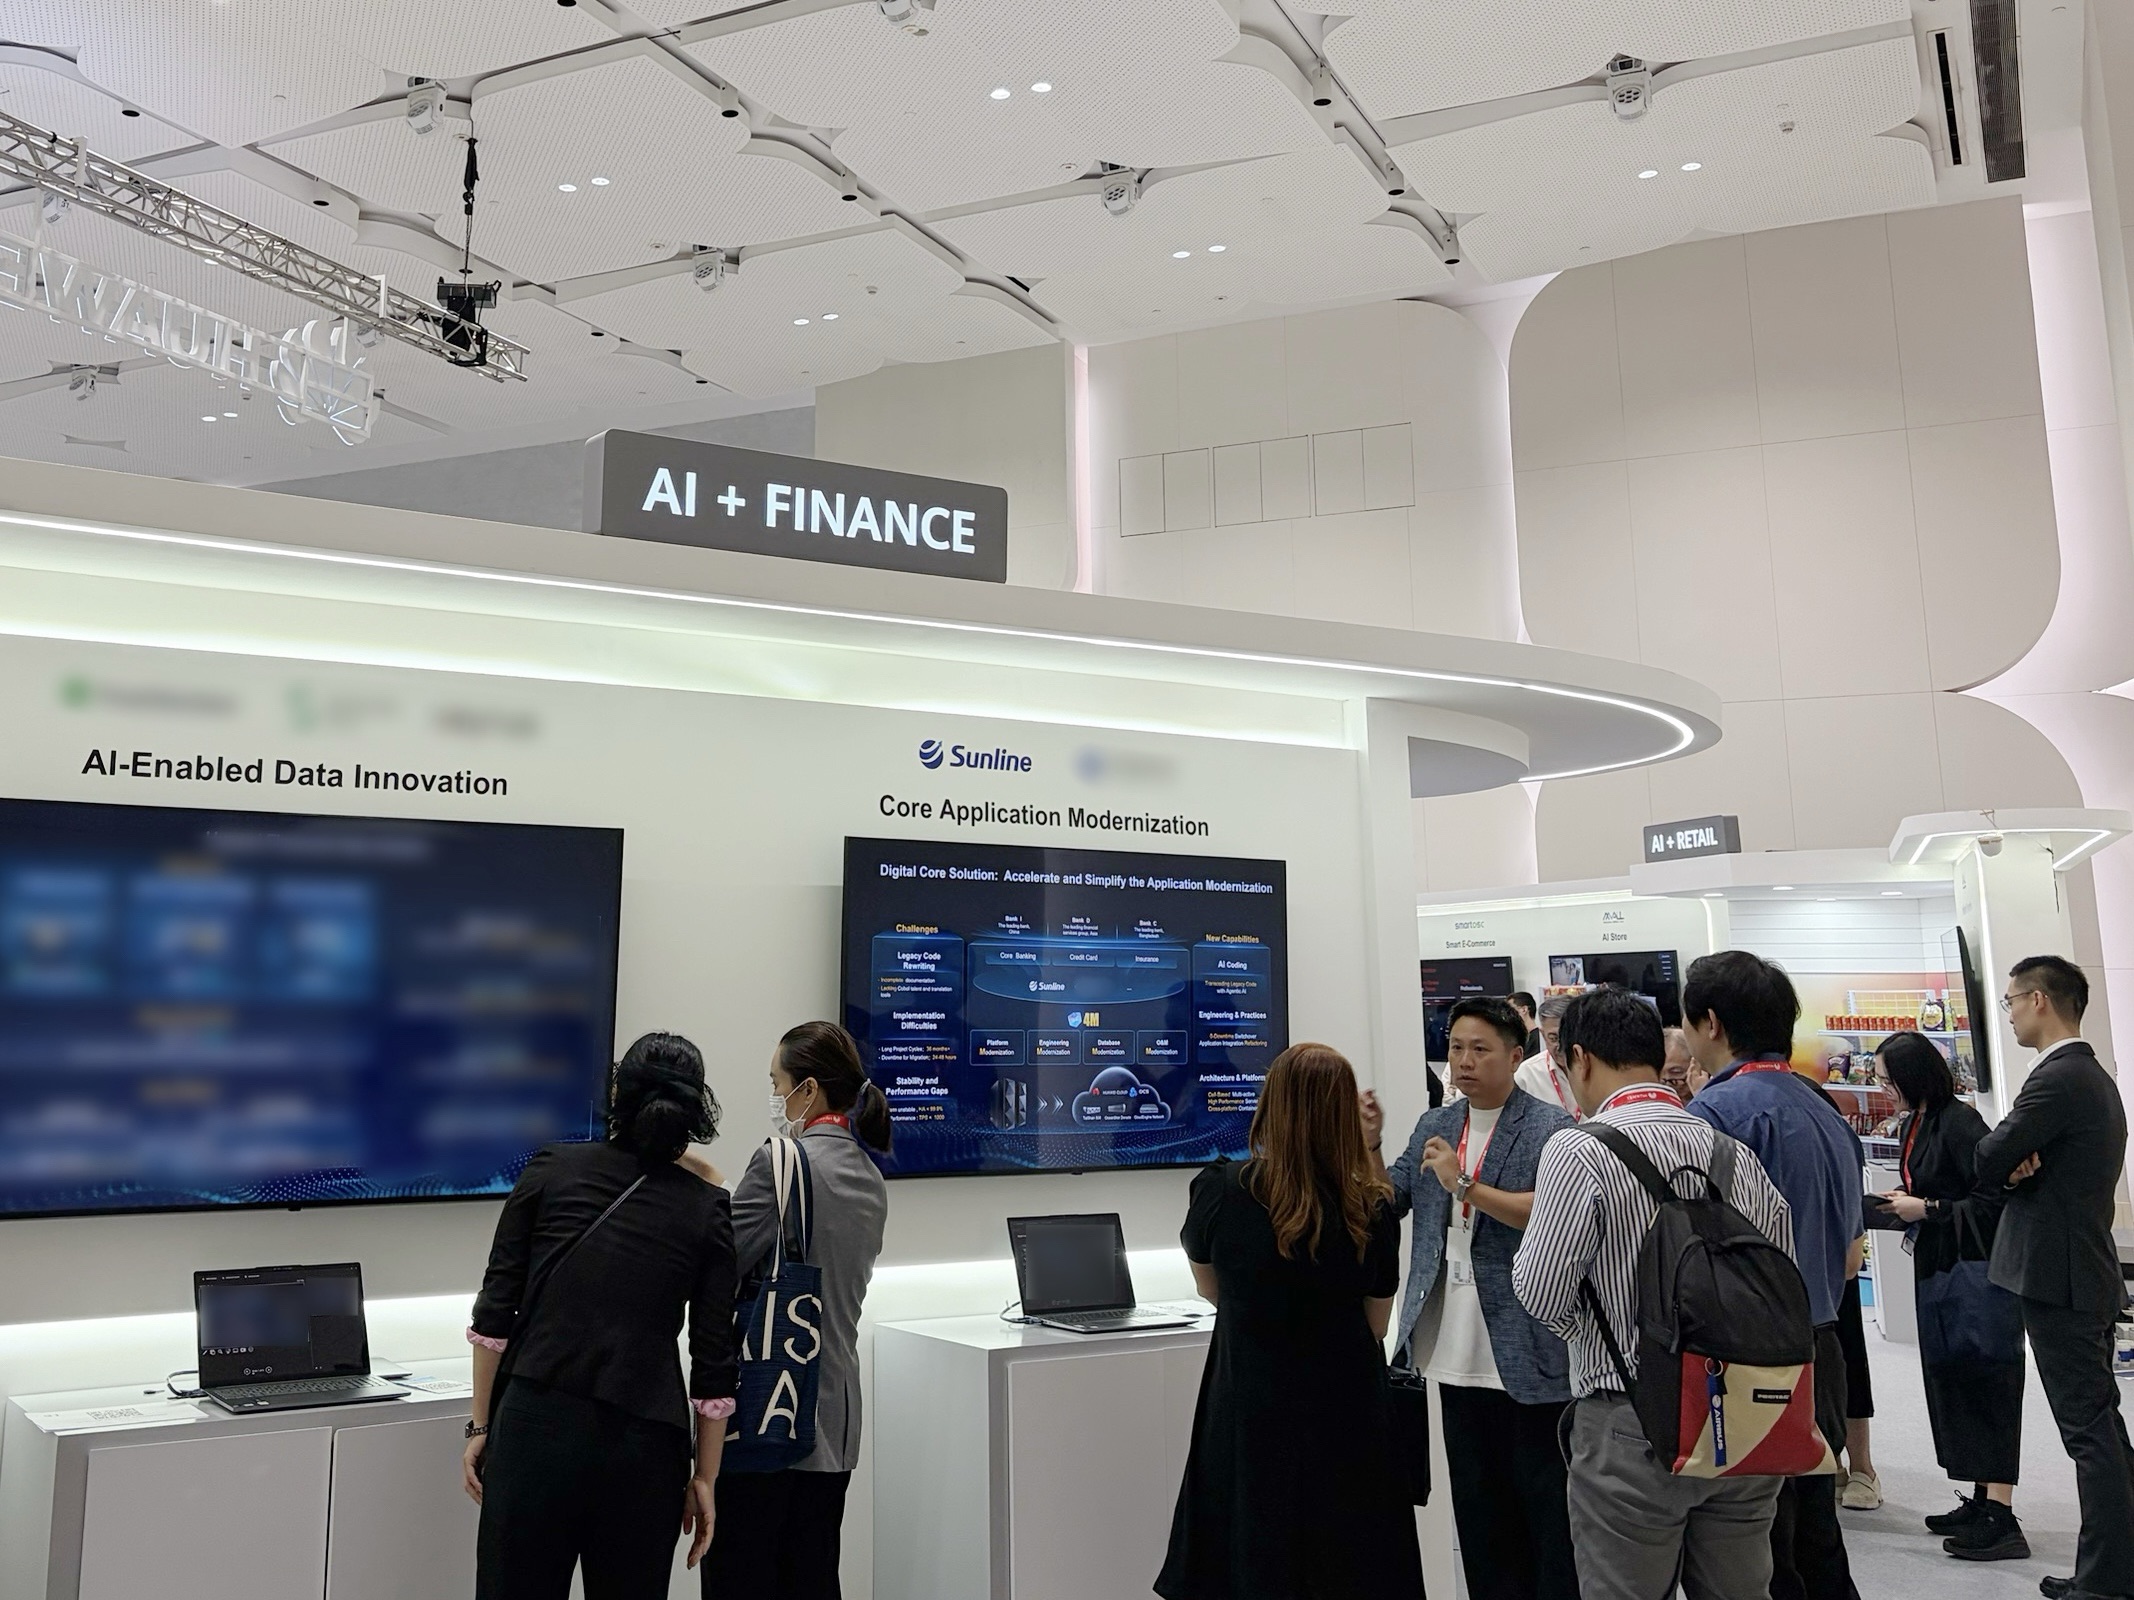
    Sunline engages with global banking customers at HUAWEI CONNECT 2026.


    Sunline and Huawei continue to deepen their partnership across banking modernization, AI innovation and international market development, bringing together complementary technology, industry expertise and implementation experience to support financial institutions across global markets.

    At the Banking Core Application Modernization & Intelligence Partner Roundtable, Sunline joined Huawei and ecosystem partners for discussions around Core Banking modernization, Agent Core and AI Coding, and how these capabilities are shaping the next phase of banking technology. Jack Wang, General Manager of New Markets at Sunline International, shared Sunline and Huawei’s overseas collaboration progress and exchanged perspectives with partners on bringing technology innovation and implementation experience to more international banking markets.


    “Core modernization is increasingly connected with advances in data, AI and software engineering. By deepening our collaboration with Huawei, we aim to bring these capabilities together across the banking technology stack and apply our combined technology and implementation experience in more international markets.” said Jack.
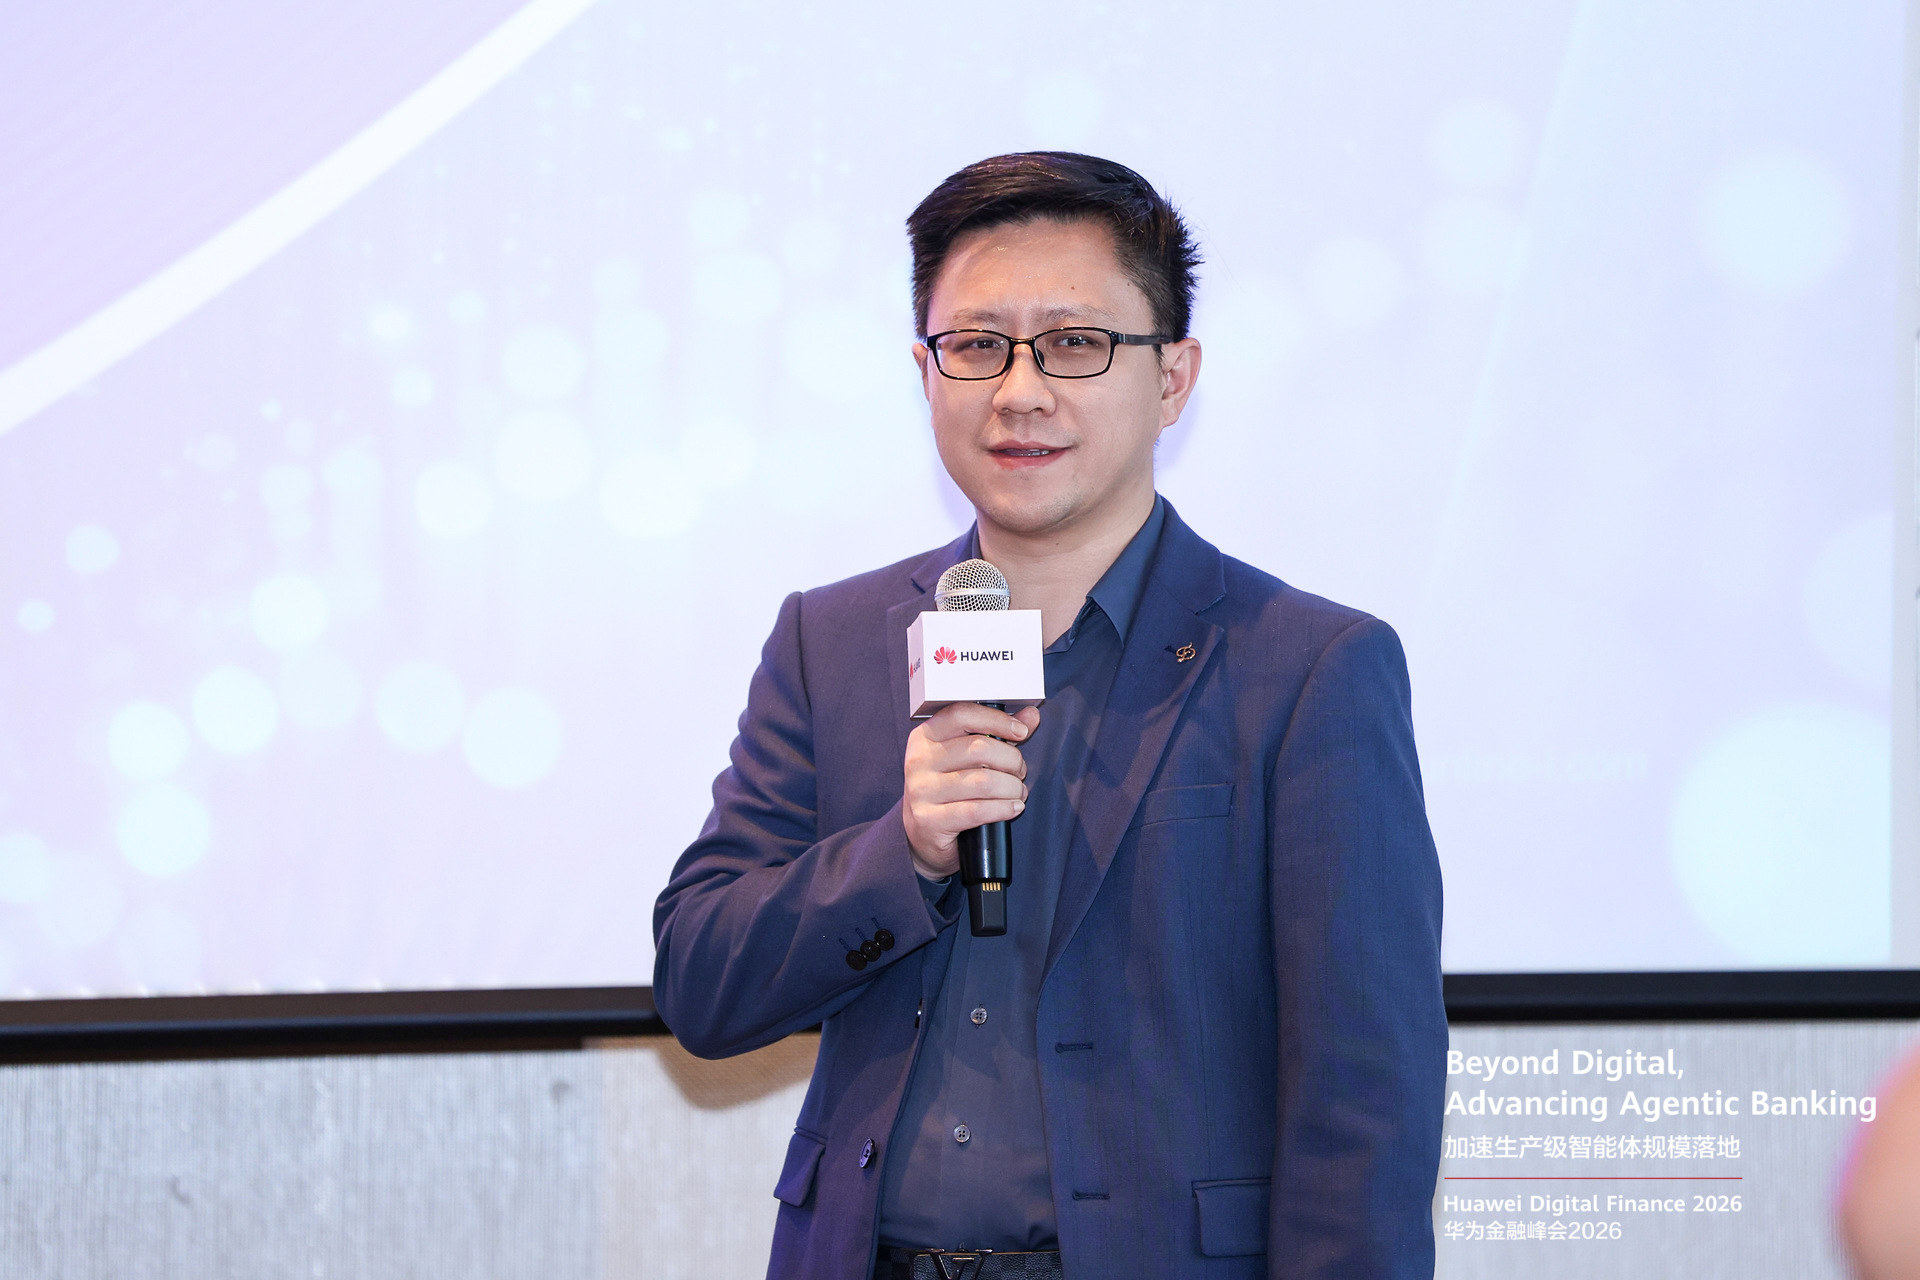

    Jack Wang, General Manager of New Markets at Sunline International, discusses the expansion of Sunline and Huawei’s technology collaboration across international markets.


    During the Banking AI Innovation Practice Forum as an important session during Huawei Connect 2026, Sunline joined Huawei and industry partners in the joint launch of the AI Coding Training Program, supporting broader industry collaboration around AI-enabled software engineering and development practices.
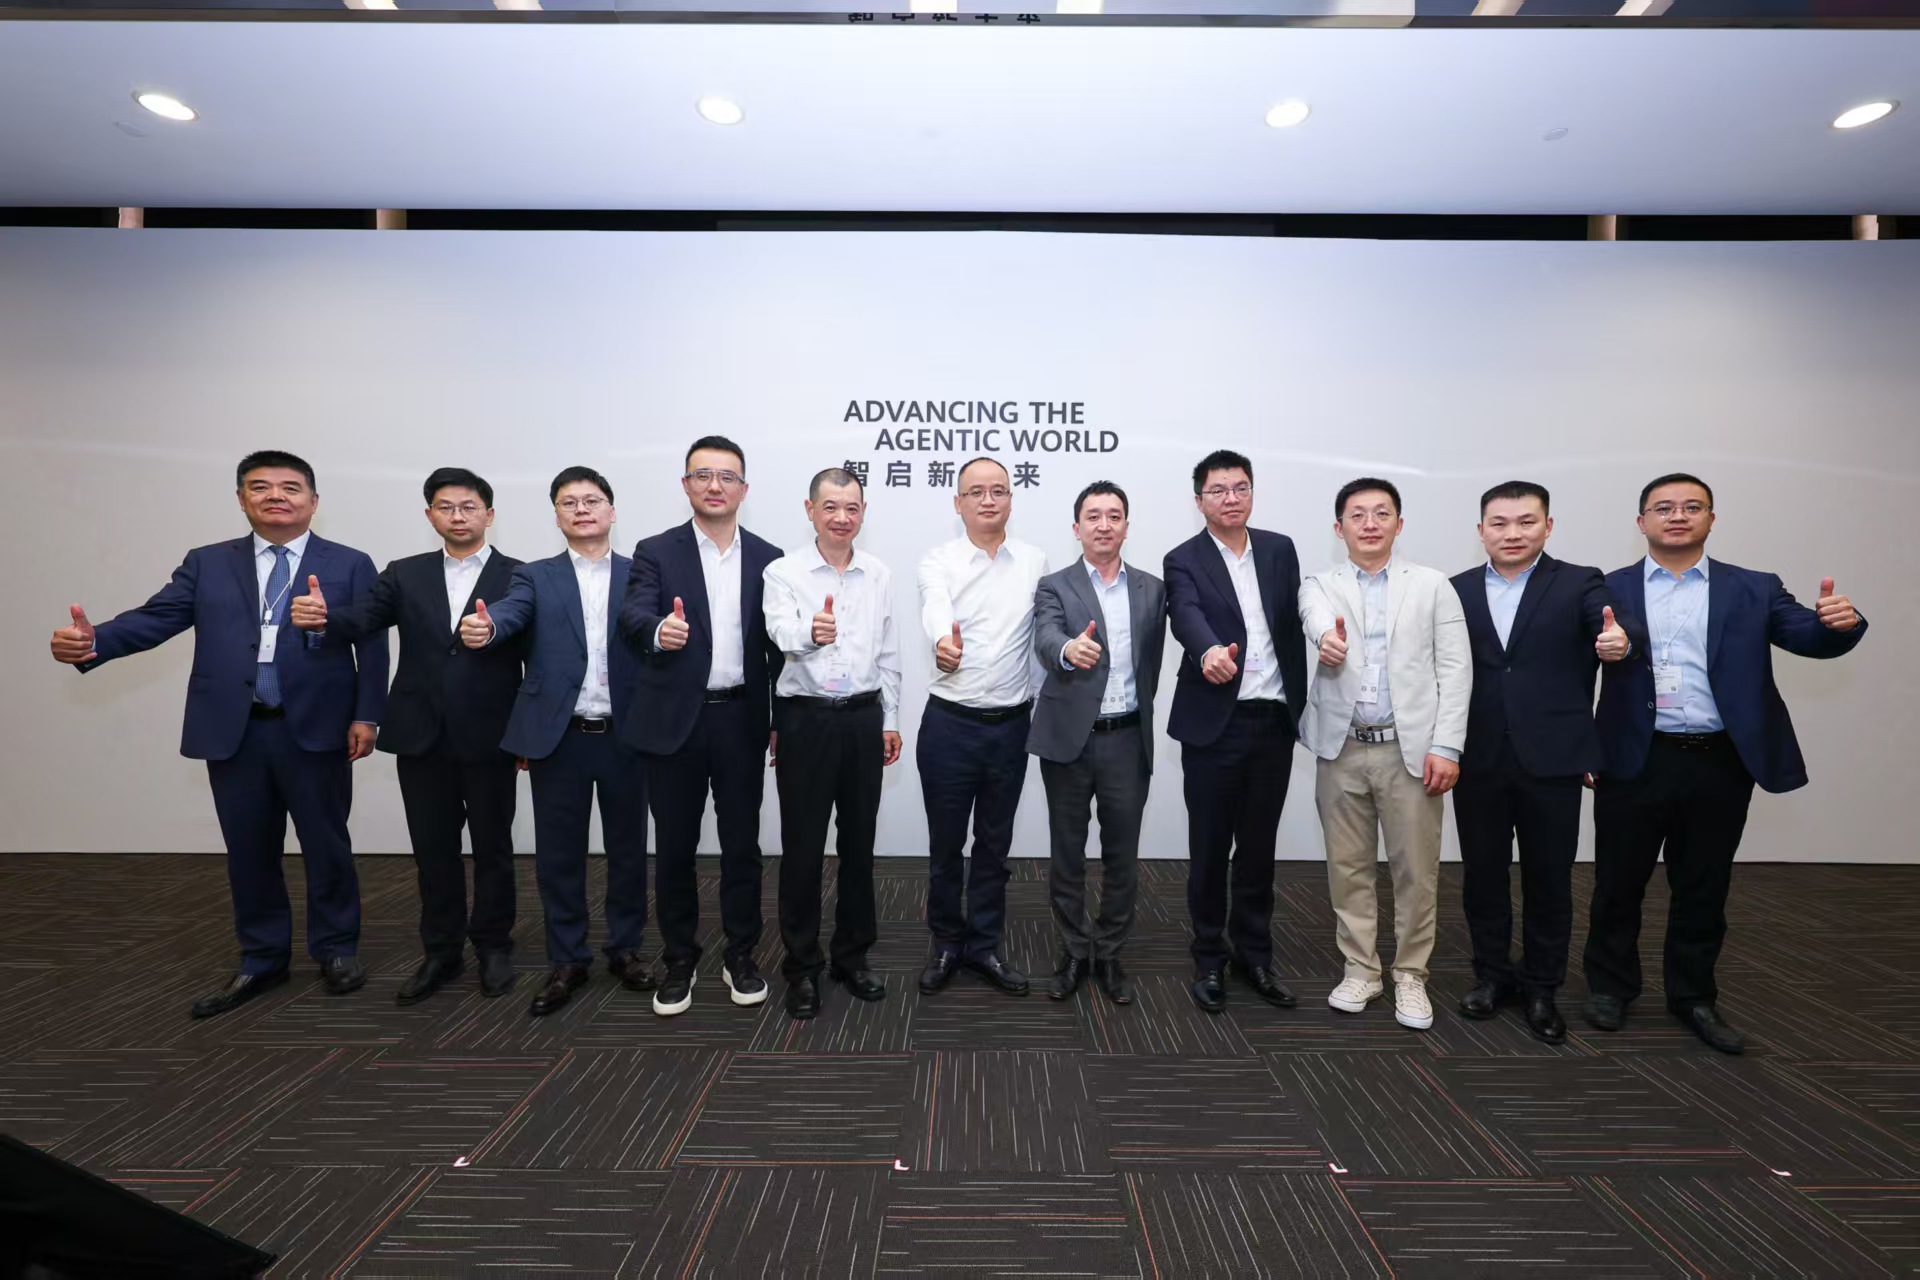
    Ruby Zhou, Sales President of Sunline International, joins Huawei and industry partners at the launch of the AI Coding Training Program.


    Today, Sunline serves more than 60 overseas financial institutions across over 10 countries and regions, with experience supporting banks across diverse regulatory, technology and business environments. This international footprint continues to shape how Sunline approaches the next generation of banking technology, with a strong focus on practical innovation that can adapt to different markets.


    HUAWEI CONNECT 2026 provides a global platform for Sunline to share this direction with banks and technology partners, exchange perspectives on the evolving role of AI in banking, and explore new opportunities for collaboration. As the industry moves toward an increasingly Agentic future, Sunline will continue to bridge proven banking technology with emerging intelligence to help shape what comes next for banking.
  • Composable Core Architectures and AI-Native Engineering: Sunline at the 23rd China-ASEAN Expo

    Composable Core Architectures and AI-Native Engineering: Sunline at the 23rd China-ASEAN Expo

    As economic integration and cross-border digital transactions accelerate across the China-ASEAN Free Trade Area, financial institutions throughout Southeast Asia face a critical architectural pivot. Legacy monoliths are increasingly unable to support high-concurrency digital volume, real-time transaction processing, and rapid ecosystem integration.

    Against this backdrop, Sunline will participate in the 23rd China-ASEAN Expo (CAEXPO) to showcase how domain-driven, composable architecture enables continuous transformation and real-time execution for modern financial institutions.

    A central challenge in core transformation is balancing rapid innovation with operational stability. Traditional monolithic migrations introduce high execution risks and lock institutions into rigid vendor roadmaps.

    Sunline addresses these structural limitations through SunCBS, acloud-native core banking system built on domain-driven, composable microservices. 


    Throughout the exhibition, Sunline will demonstrate its end-to-end technology portfolio designed for digital-first financial institutions, including the cloud-native core banking system, integarted date platforms, AI-native software engineering, and digital currency (e-CNY) infrastructure. 

    Alongside solution demonstrations, Sunline technical architects will present two briefings detailing practical AI deployment across core operations and data management:

    · Sept 17 | 16:40 – 17:00 DataMind: An Integrated Data Management Platform in the AI Era


    · Sept 18 | 11:20 – 11:40 Luban: AI-Native SDLC for SunCBS

    CAEXPO provides an opportunity to examine proven implementation models that balance agility with financial-grade resilience.

    Visiting the Sunline team at Booth B1-A020 offers practical insights into establishing flexible, scalable architectures tailored to the evolving demands of ASEAN financial markets.

    Event Details

    Date: September 17–21, 2026

    Location: Nanning International Convention and Exhibition Center, Nanning, China

    Sunline Booth: B1-A020

    See you in Nanning!

  • Sunline and AWS Advance Core Modernisation and AI Readiness Dialogue at The Asian Banker Thailand Awards 2026

    Sunline and AWS Advance Core Modernisation and AI Readiness Dialogue at The Asian Banker Thailand Awards 2026

    Banking leaders examine how resilience, legacy pressures and AI readiness are reshaping the technology agenda for the next generation of banking.


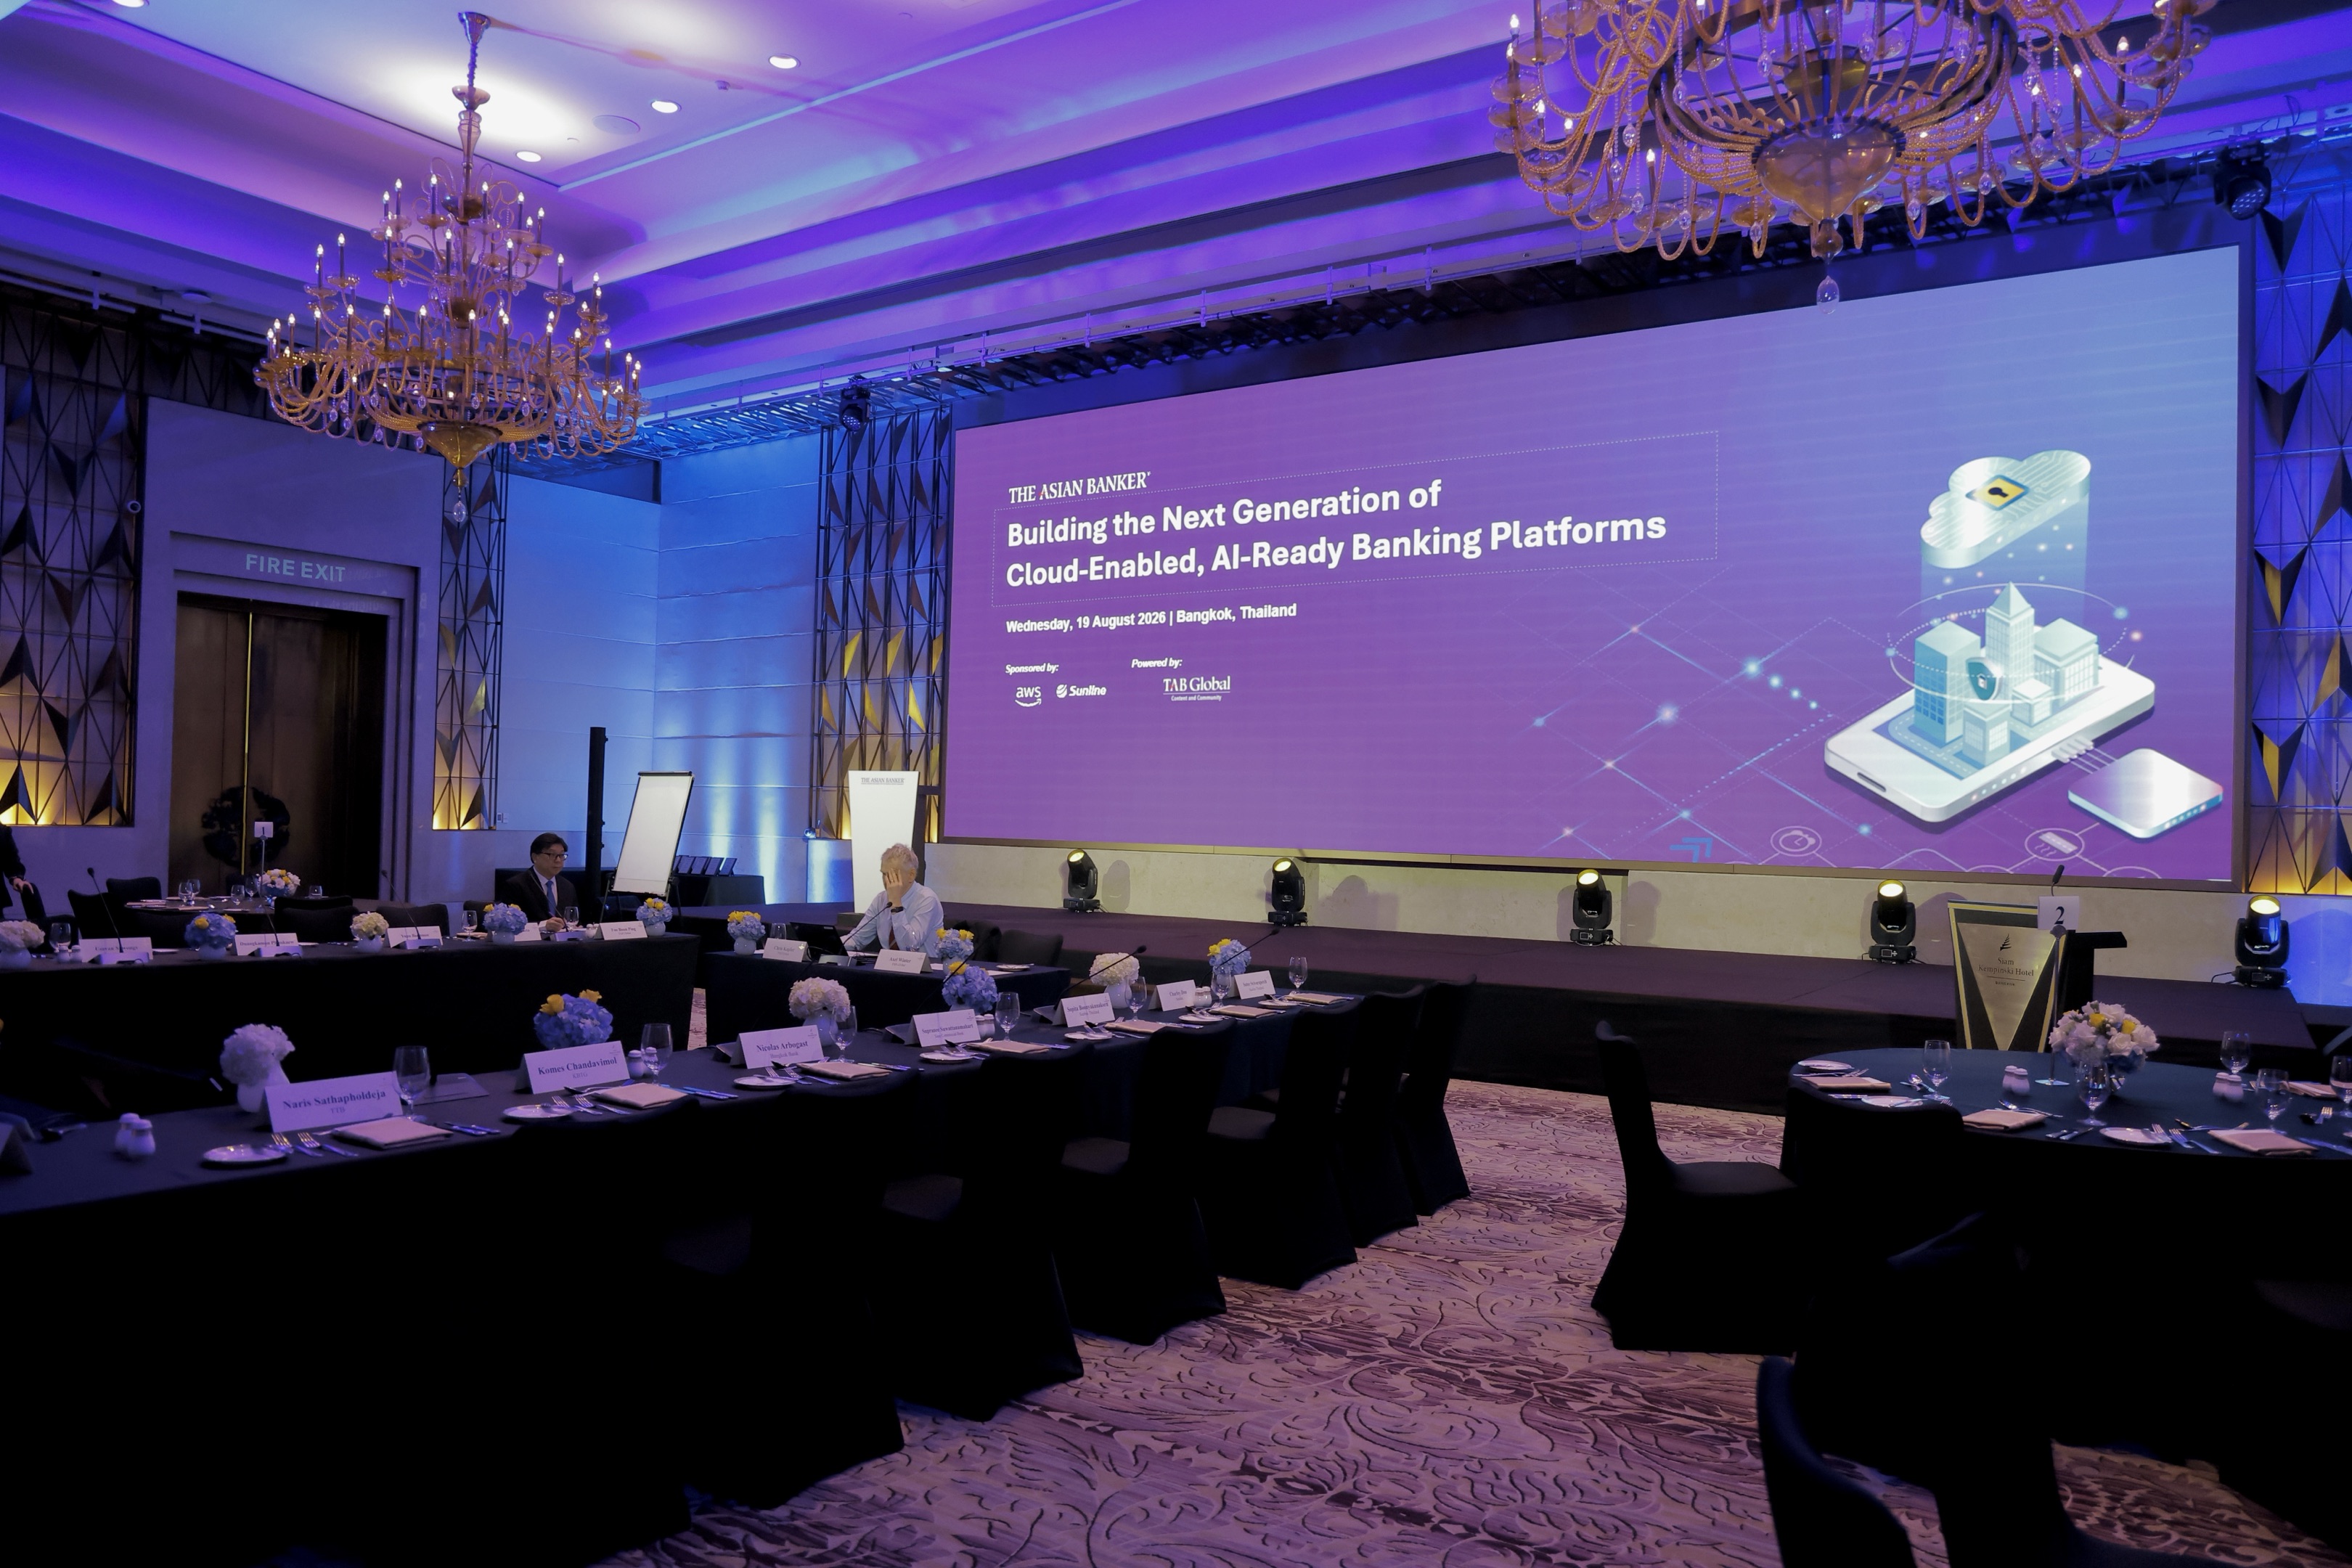
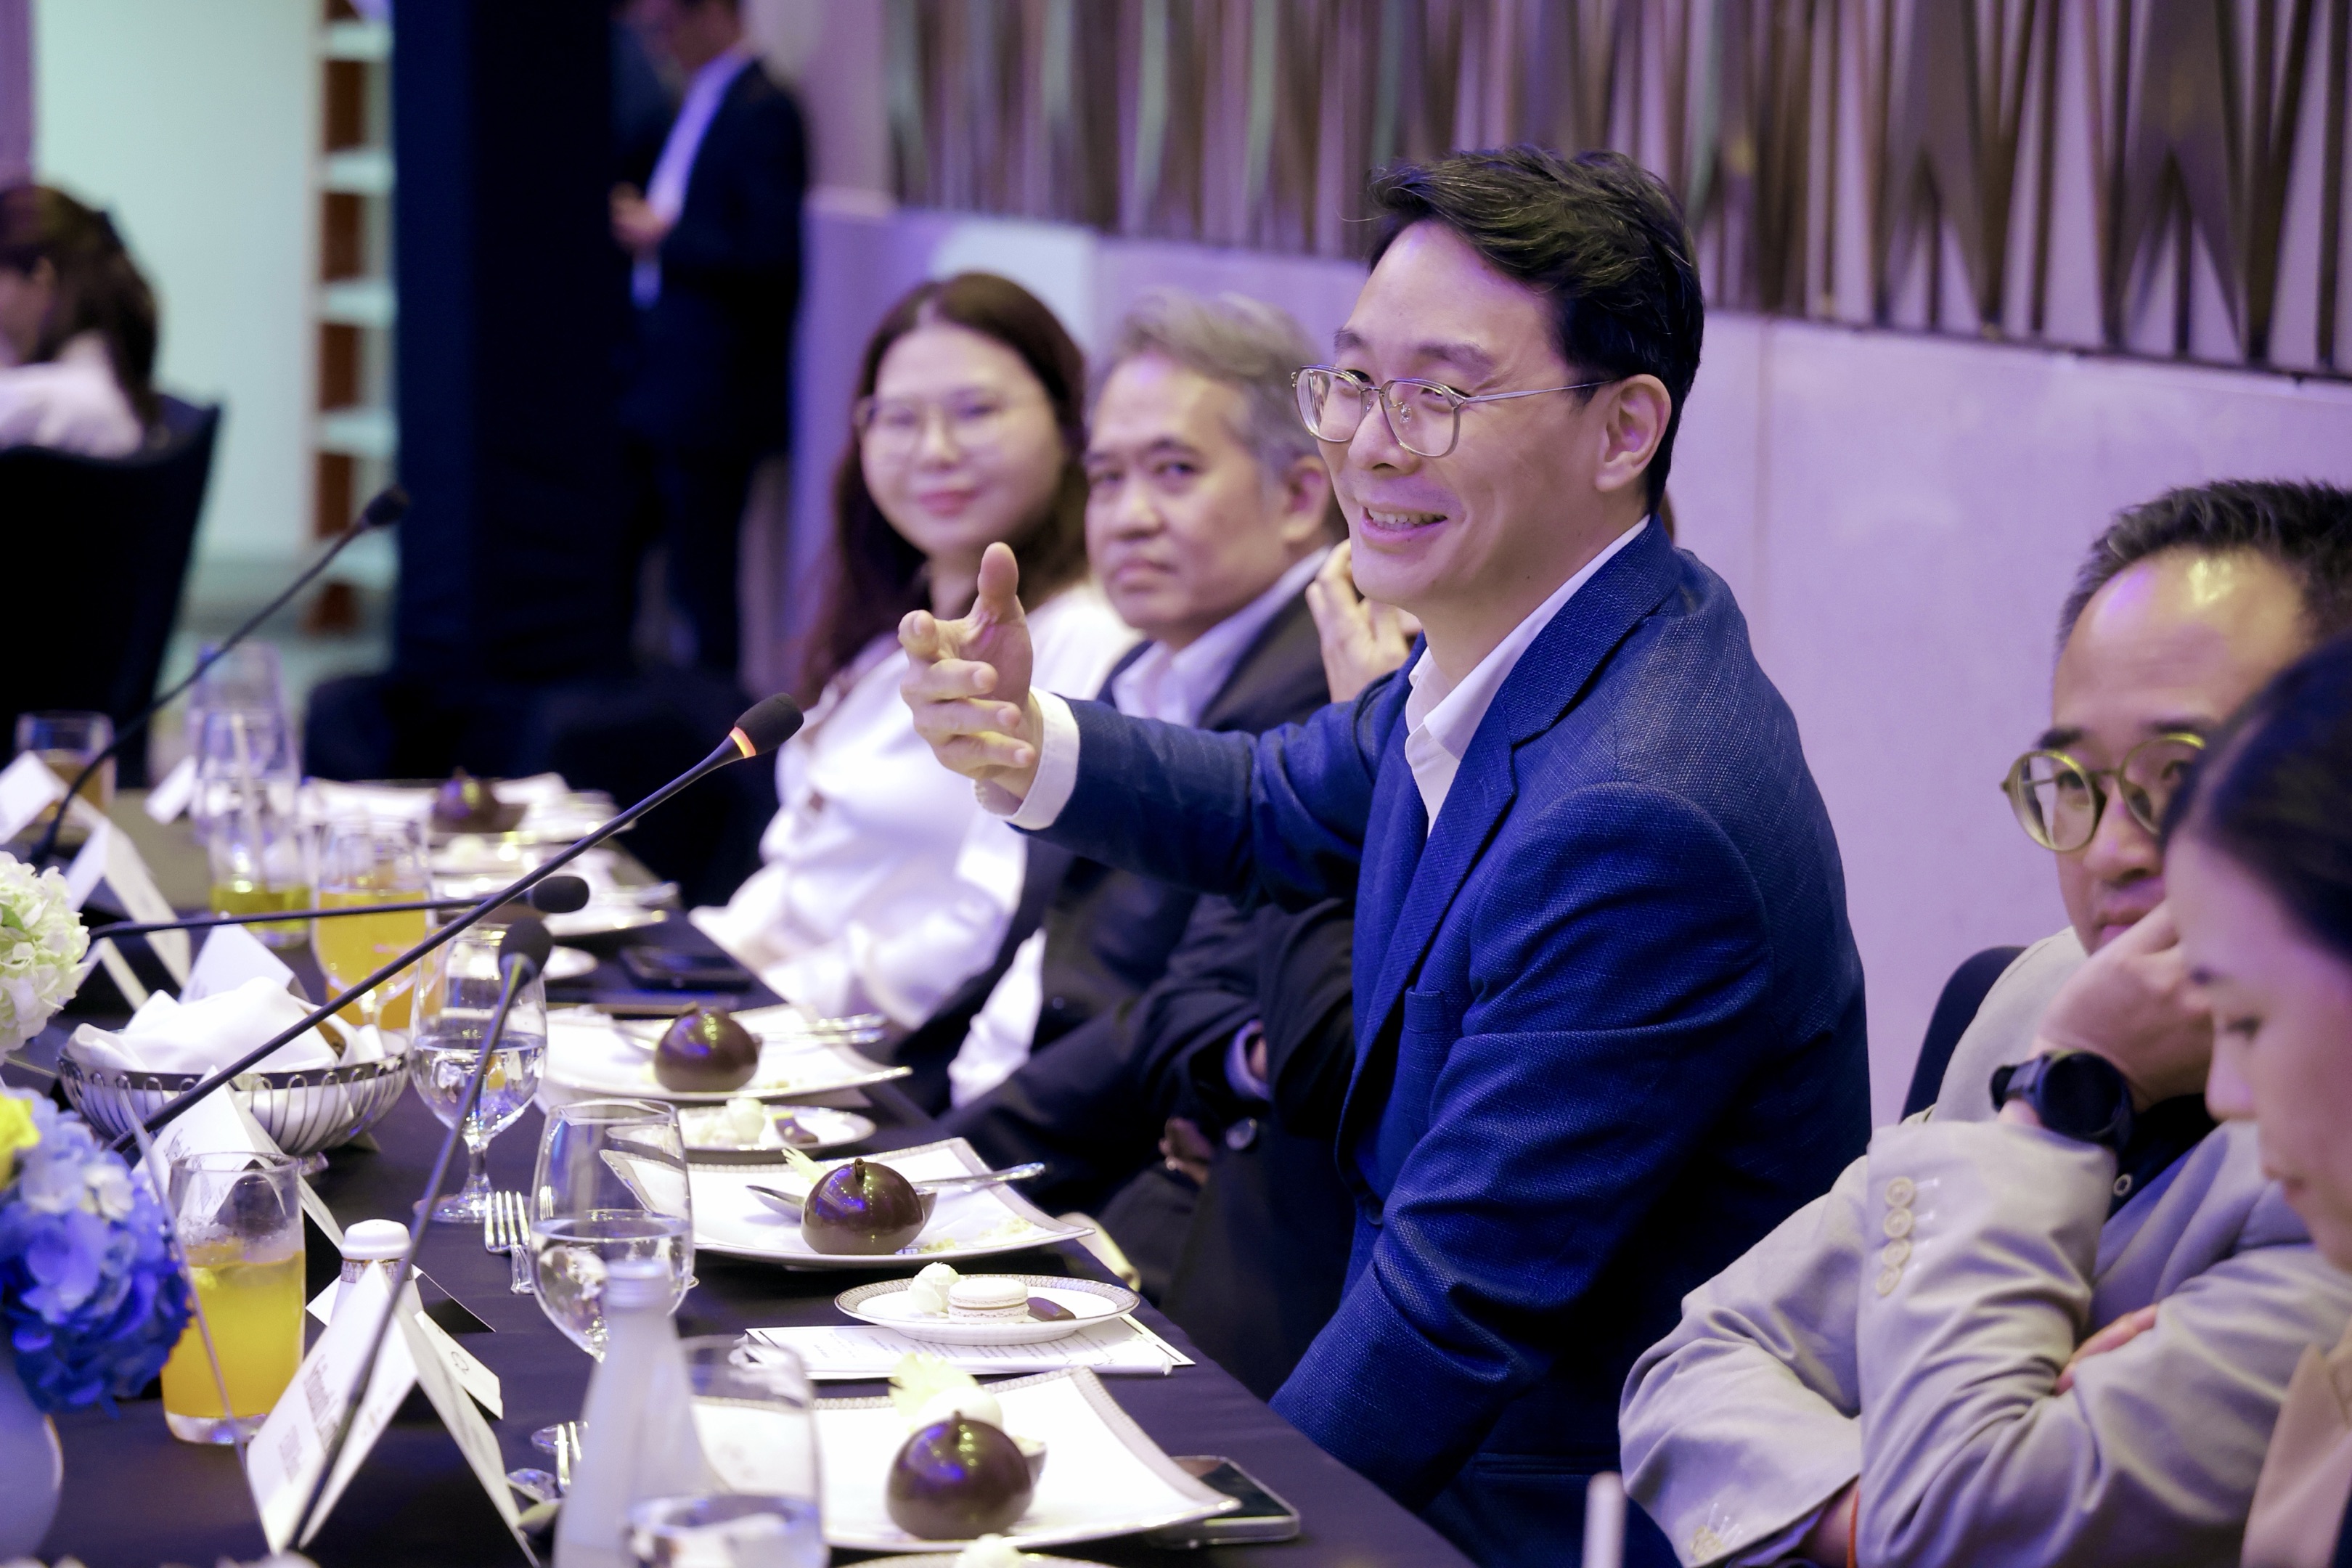
    BANGKOK, Thailand, 19 August 2026 – Amazon Web Services (AWS), in partnership with Sunline, convened banking leaders at The Asian Banker Thailand Awards 2026 for an Executive Roundtable on “Next-Gen Cloud-Enabled, AI-Ready Banking Platforms.”

    Moderated by Christian “Chris” Kapfer, Head of Research at The Asian Banker, and Axel Winter, International Resource Director, the discussion explored a question becoming increasingly consequential for financial institutions: how to build the capacity to evolve while preserving the resilience, control and continuity required of mission-critical banking.

    The conversation brought together perspectives on legacy technology, scalability, transformation risk and the foundations required for enterprise AI, pointing to a broader shift in how banks are approaching core modernisation.

    Legacy Pressure Is Becoming A Business Resilience Issue

    Legacy systems continue to underpin critical banking operations. The challenge is increasingly the environment around them.

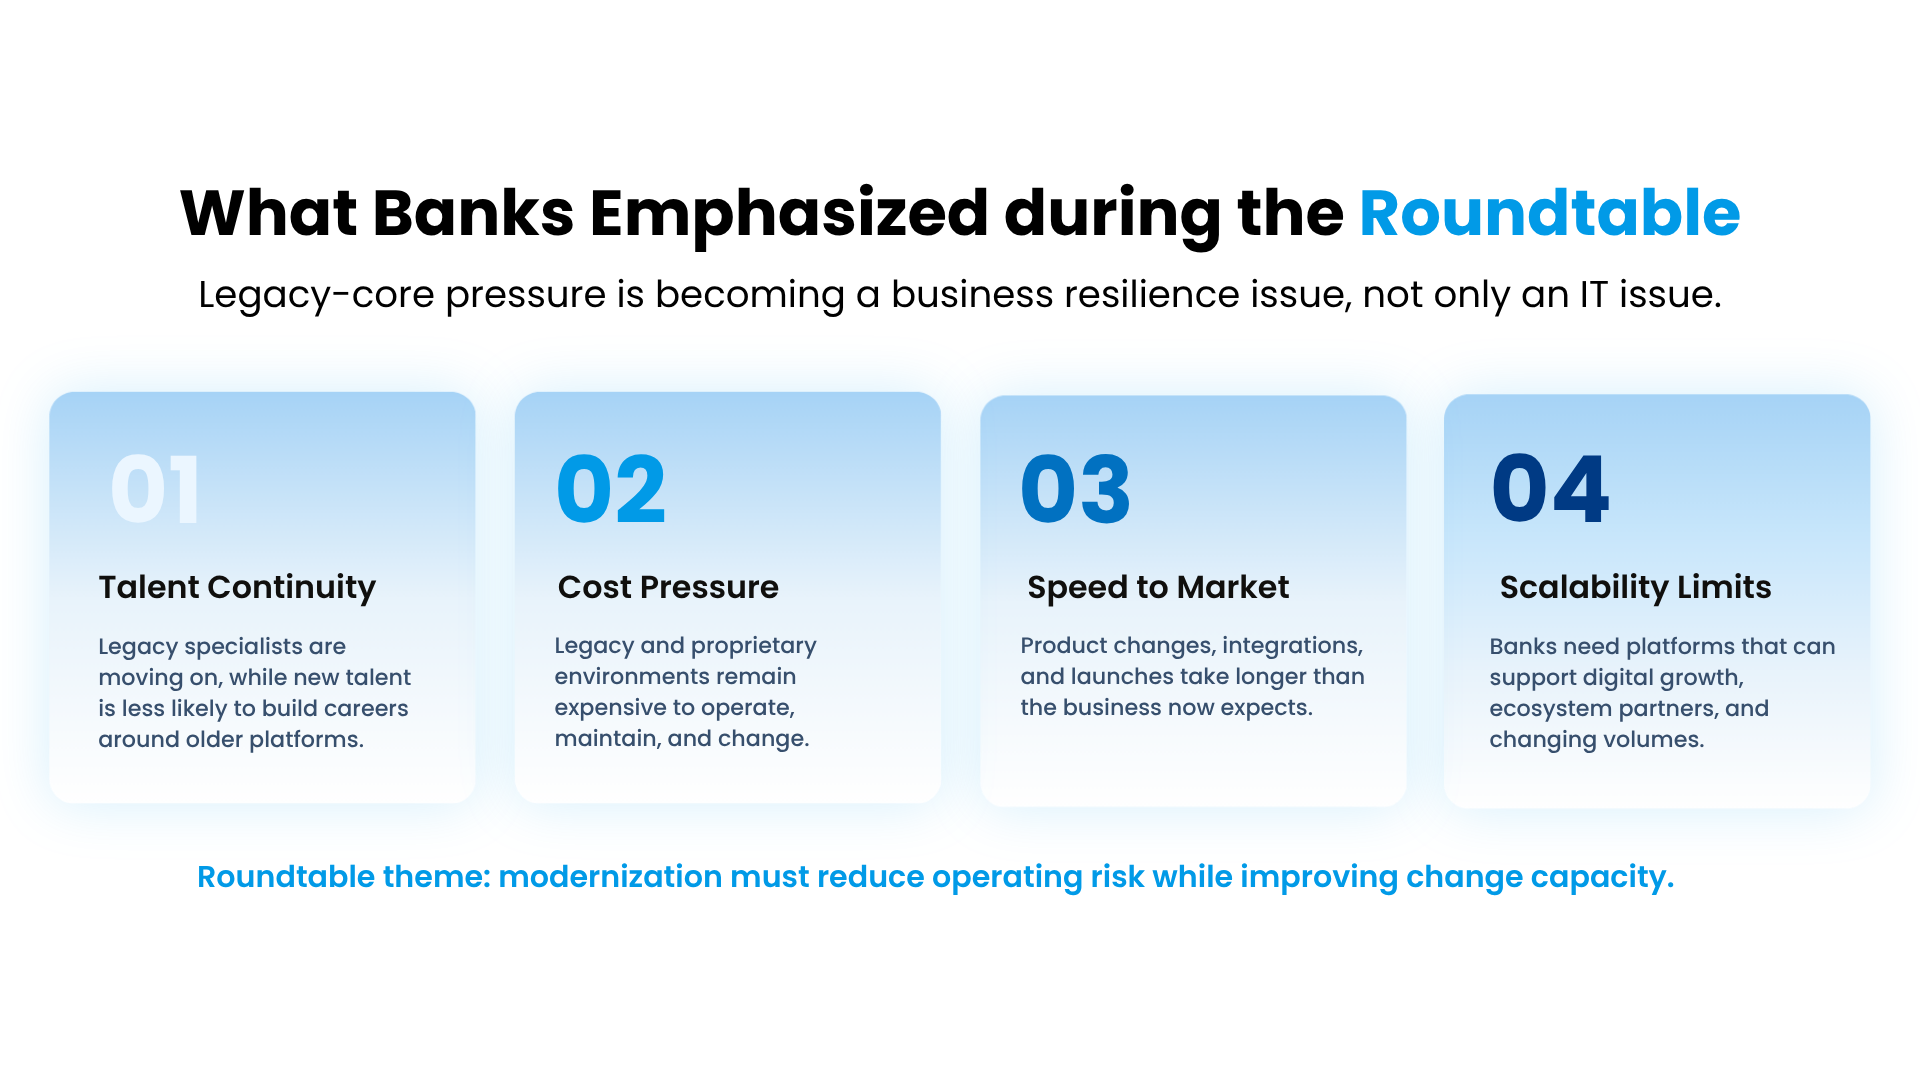
    Banking leaders highlighted four interconnected pressures: talent continuity, cost, speed to market and scalability. Legacy expertise is becoming harder to sustain, established environments remain costly to operate and change, while growing digital expectations are placing greater demands on how quickly banks can launch, integrate and scale.

    Figure 1. Key legacy-core pressures highlighted by banking leaders during the executive roundtable.


    Taken individually, these can appear to be separate operational challenges. Collectively, they point to a more structural question: whether the bank’s technology foundation can continue to support the pace and direction in which the institution needs to evolve.


    This is moving core modernisation beyond a conventional infrastructure renewal programme and closer to the strategic agenda of the bank.


    From System Replacement to Change Capacity

    For Sunline, the implications extend beyond the question of when to replace a legacy core. Stability and control remain fundamental to banking. But institutions increasingly need those qualities alongside greater adaptability, scalability and the ability to change continuously.


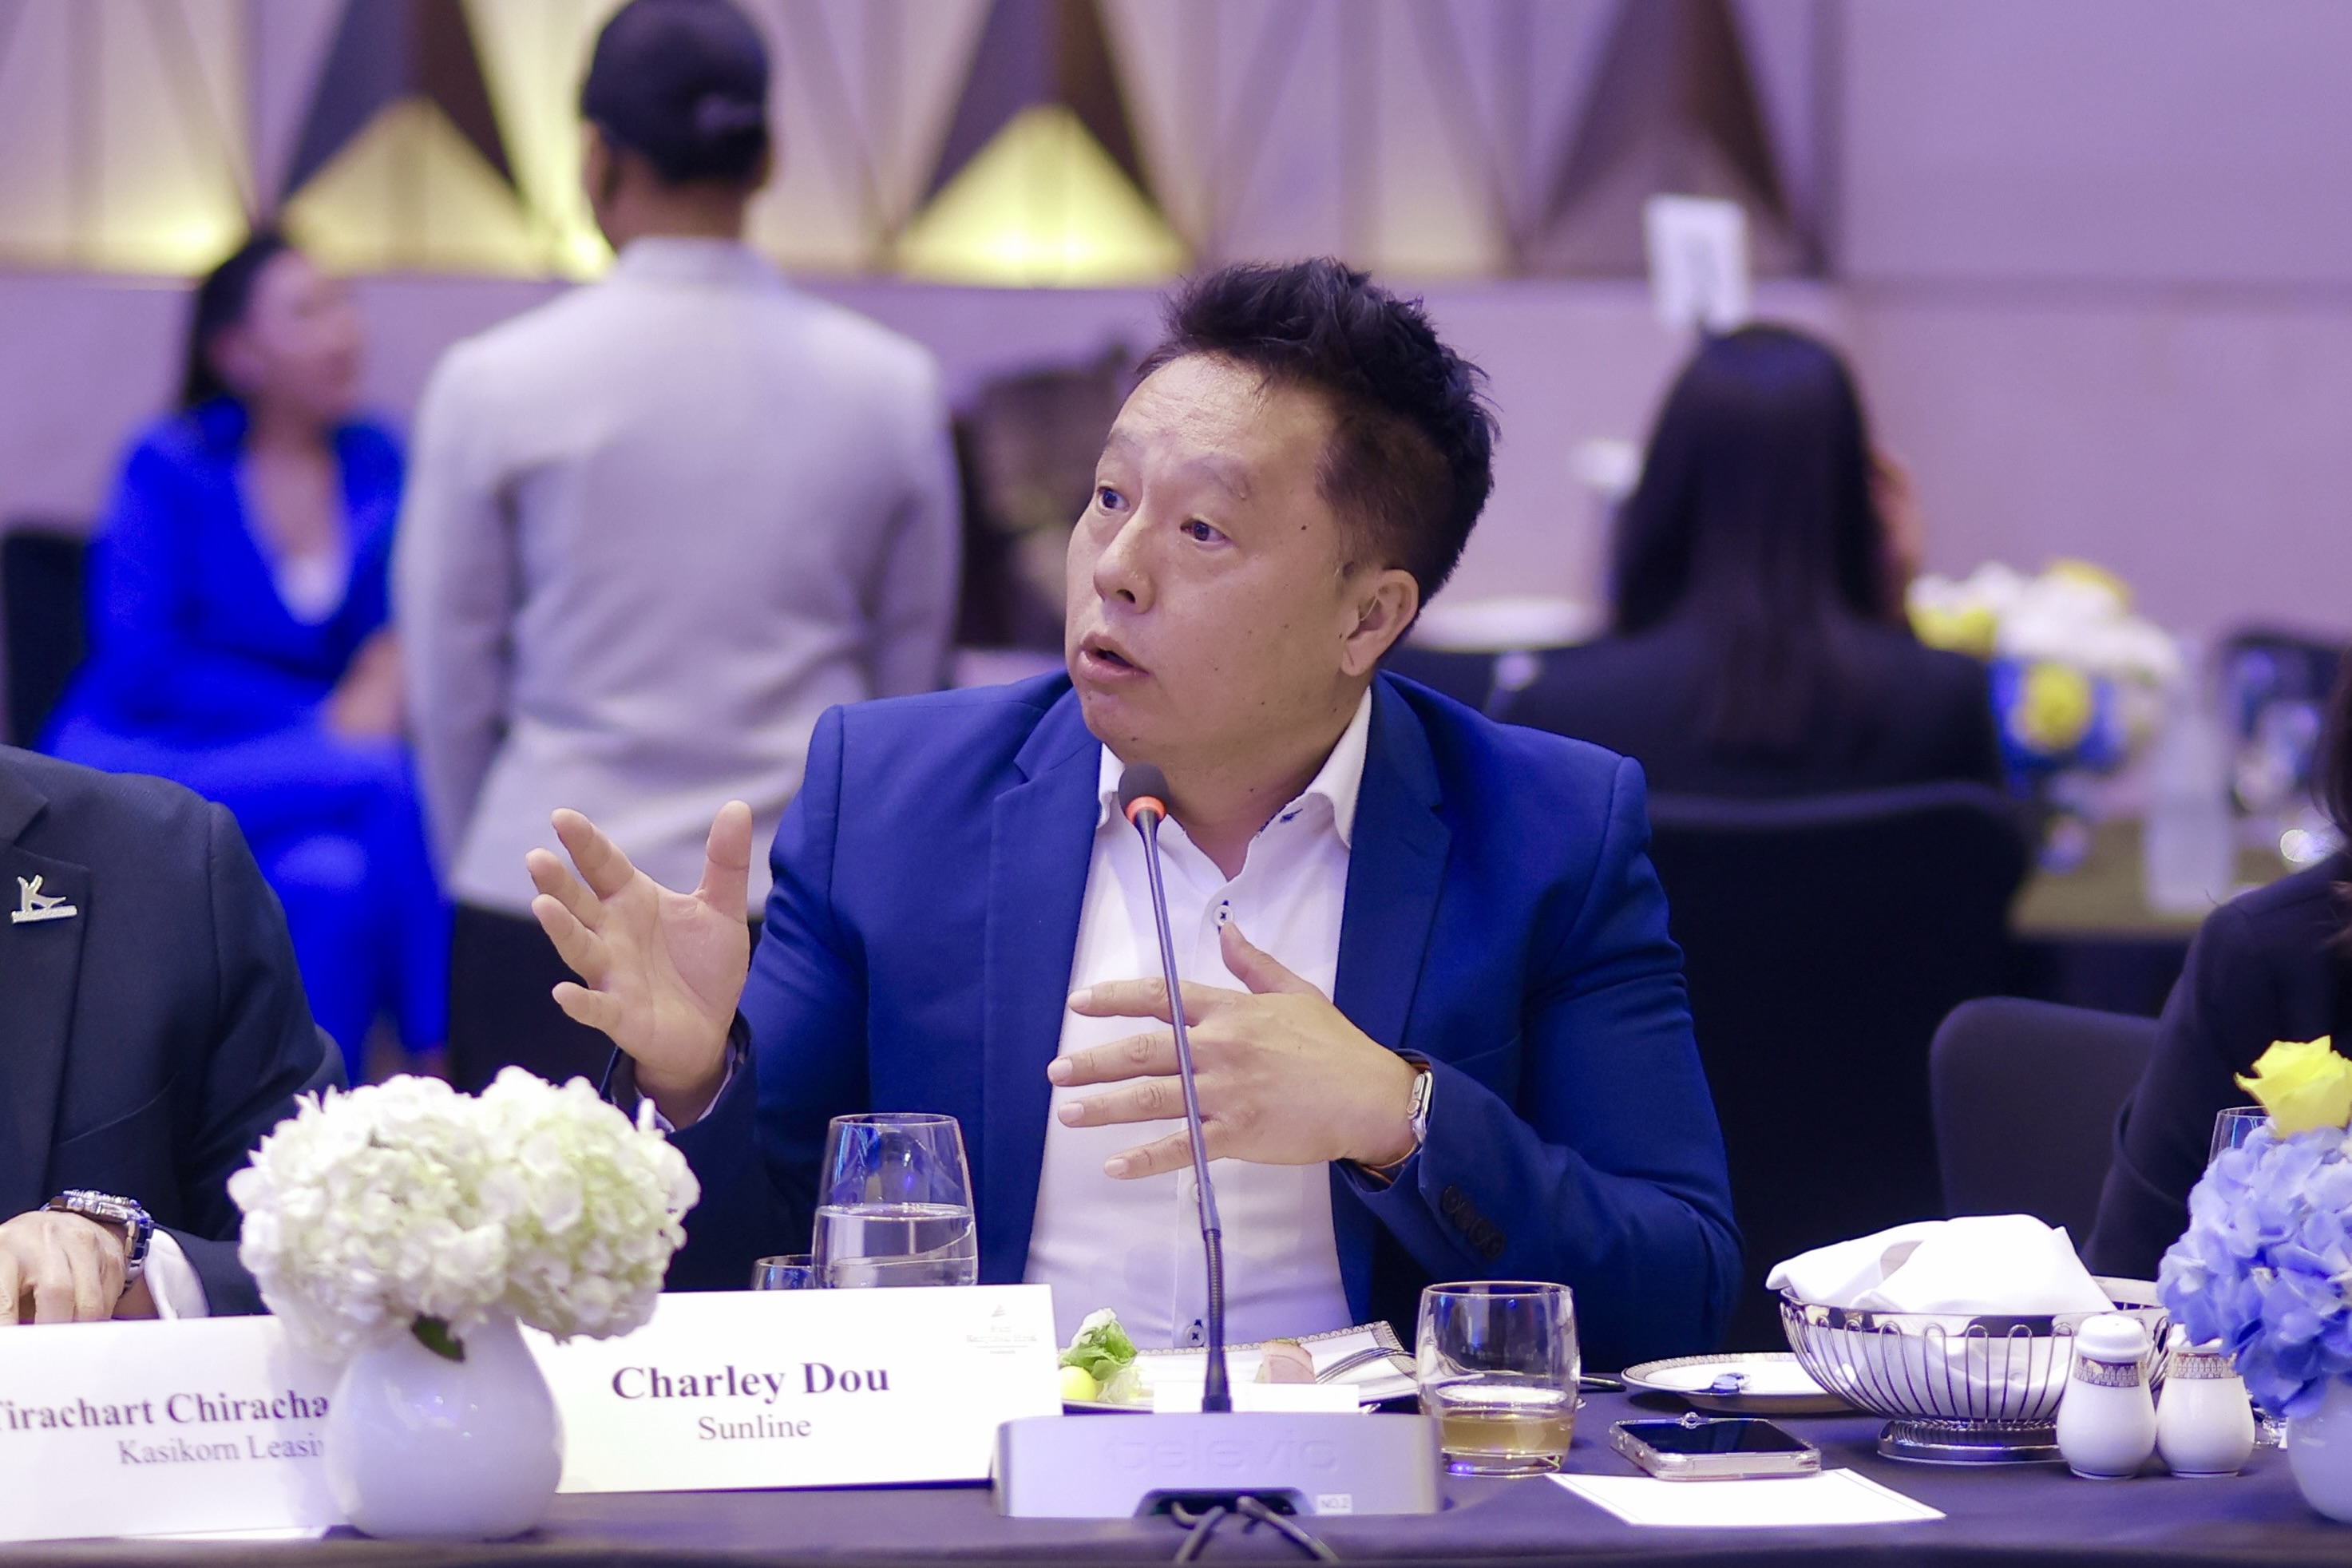
    Charley Dou of Sunline highlighted that this makes modernisation as much a question of long-term change capacity as technology architecture.


    “Modernisation is not one model for every institution. The strategic question is how banks create greater capacity to evolve without compromising the resilience on which their business depends. The right approach must reflect each institution’s complexity, risk appetite and business priorities.” 

    Charley Dou, Solutions Expert, Sunline


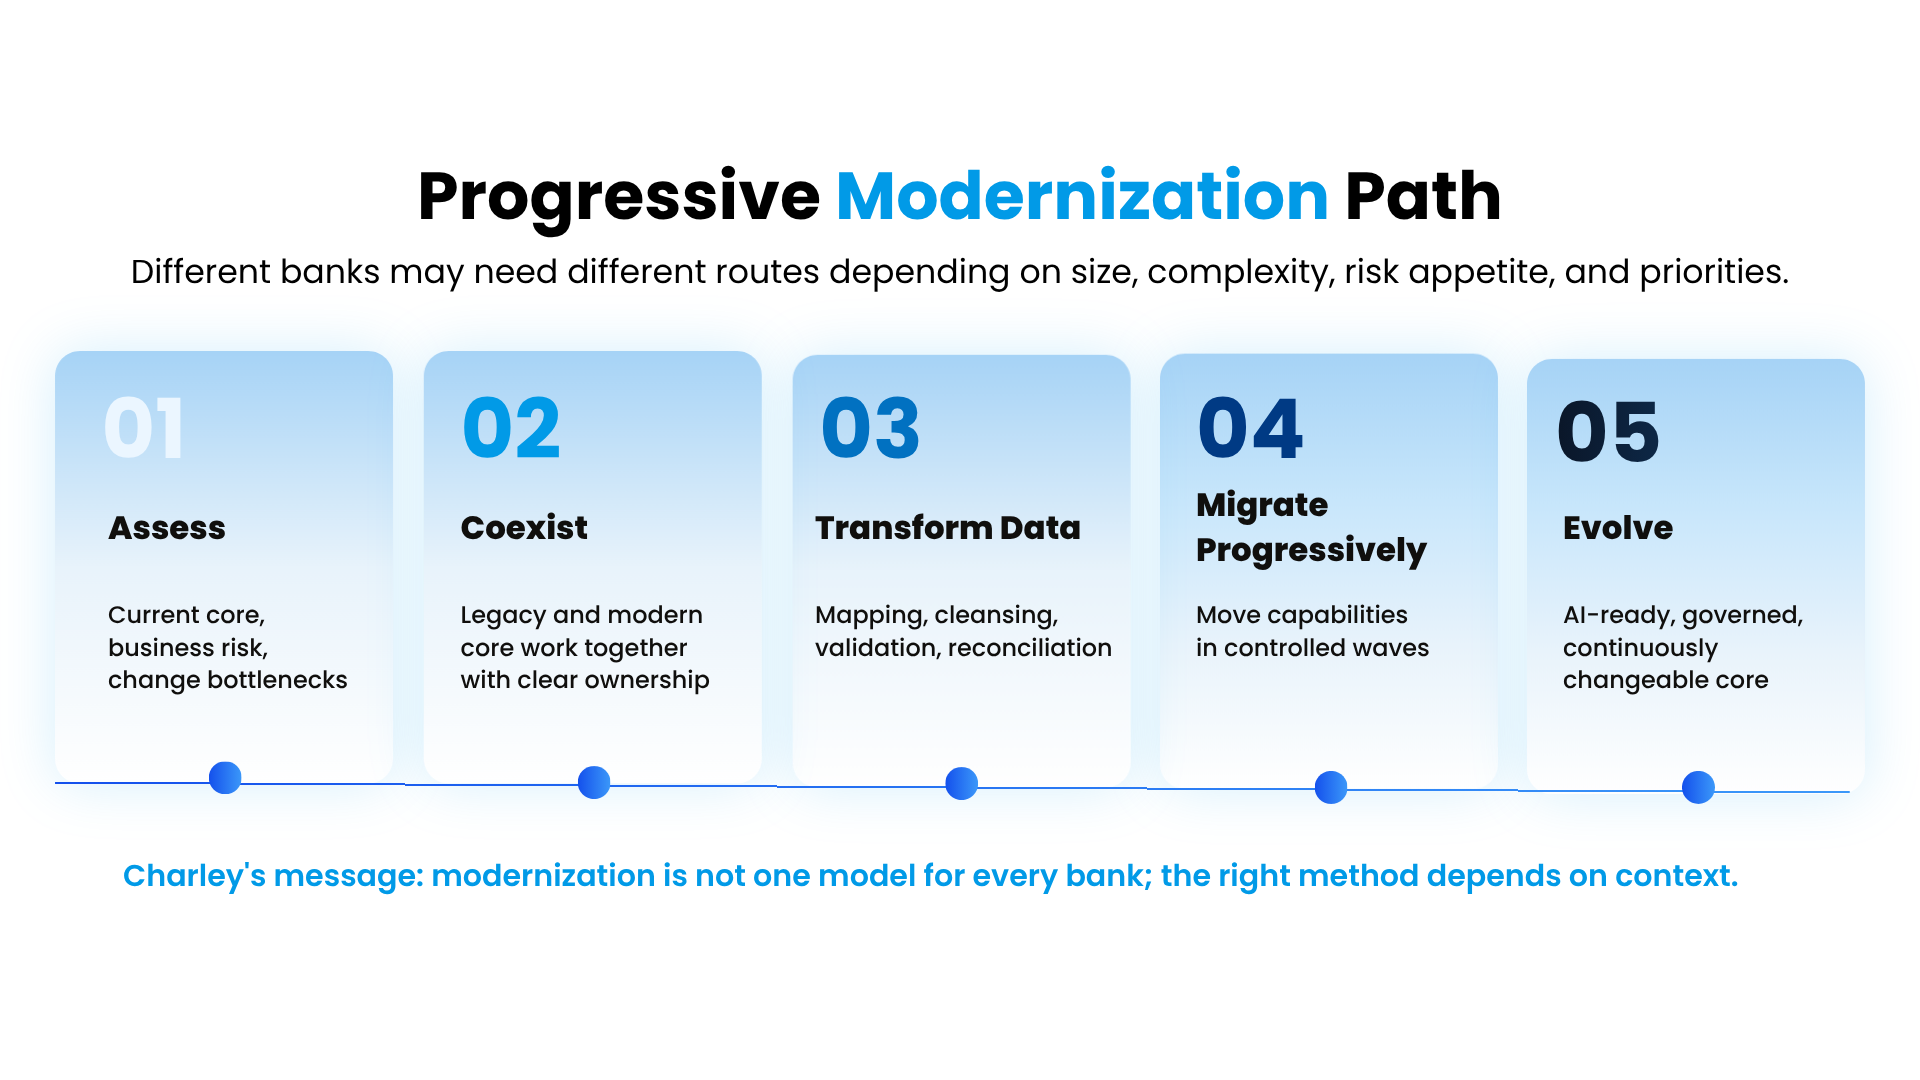
    Rather than forcing every institution towards the same transformation model, banks can consider different routes according to their starting point and priorities. Some may pursue a more direct replacement, while others may benefit from progressive migration or a period of coexistence between legacy and modern environments.

    Figure 2. A progressive modernisation approach can help banks manage transformation risk while building greater capacity for change.


    The significance of a progressive approach is not simply that transformation can happen in stages. It is that banks can align the pace of change with their operational readiness and risk profile. That places greater emphasis on how the transition is governed, not only on the target architecture.


    Execution Becomes Part of the Strategy

    Coexistence between legacy and modern environments introduces its own complexity. Clear architecture, reliable integration, data synchronisation, reconciliation and operational ownership become critical when two environments need to operate simultaneously.


    The same applies to data transformation. Migration cannot be reduced to the technical movement of data. Mapping, cleansing, validation, reconciliation, cutover planning and rollback readiness all contribute to whether the transition can be executed without compromising business continuity.


    Drawing on Sunline’s experience in Thailand, Sutee emphasised the importance of execution discipline in translating modernisation strategy into operational outcomes.


    “Successful modernisation depends on more than the technology itself. A clear roadmap, realistic migration stages, strong data governance and continuous business validation are essential to moving forward while maintaining control over business continuity, data integrity and customer impact.”

    Sutee Srivorapetch, Sunline Thailand


    This experience points to an important distinction: modernisation risk is not managed by slowing transformation, but by structuring transformation in a way that allows change to happen with control.


    AI Readiness Starts with the Foundations Beneath It

    AI adds greater urgency to this conversation. Banks are increasingly exploring how AI can improve productivity, customer insight, business intelligence and decision-making. Yet moving from experimentation to meaningful enterprise adoption places greater demands on the foundations beneath those capabilities.


    Trusted data, clear governance and reliable systems of record become more important as AI moves deeper into banking processes. Without those foundations, AI can introduce another layer of complexity rather than create sustainable value.


    This creates a direct connection between core modernisation, data modernisation and AI readiness. They are increasingly not separate technology agendas, but interconnected elements of how banks prepare their institutions for the next phase of change.


    Building the Capacity to Evolve

    The discussion in Bangkok underscored a broader shift in the modernisation agenda. Core transformation is no longer simply about replacing ageing technology. It is about reducing structural constraints while strengthening the resilience and adaptability of the institution.


    There is no universal path forward. Modernisation can be progressive, coexistence can be governed, and migration risk can be managed through clear methodology, strong governance and disciplined execution.


    Through its partnership with AWS, Sunline continues to engage financial institutions on how these foundations can support the next generation of resilient, scalable and AI-ready banking.


    Ultimately, the future of core banking will not be defined by technology replacement alone. It will be defined by whether banks have the capacity to evolve continuously, confidently and at the pace their markets demand.

  • Sunline Expands Core Banking Footprint Through Two New City Commercial Bank Projects

    Sunline Expands Core Banking Footprint Through Two New City Commercial Bank Projects

    Regional commercial banks are facing increasing pressure to modernize their technology foundations as digital transaction volumes rise and regulatory requirements evolve. Technology strategies are increasingly moving beyond system replacement towards broader business capability transformation. 


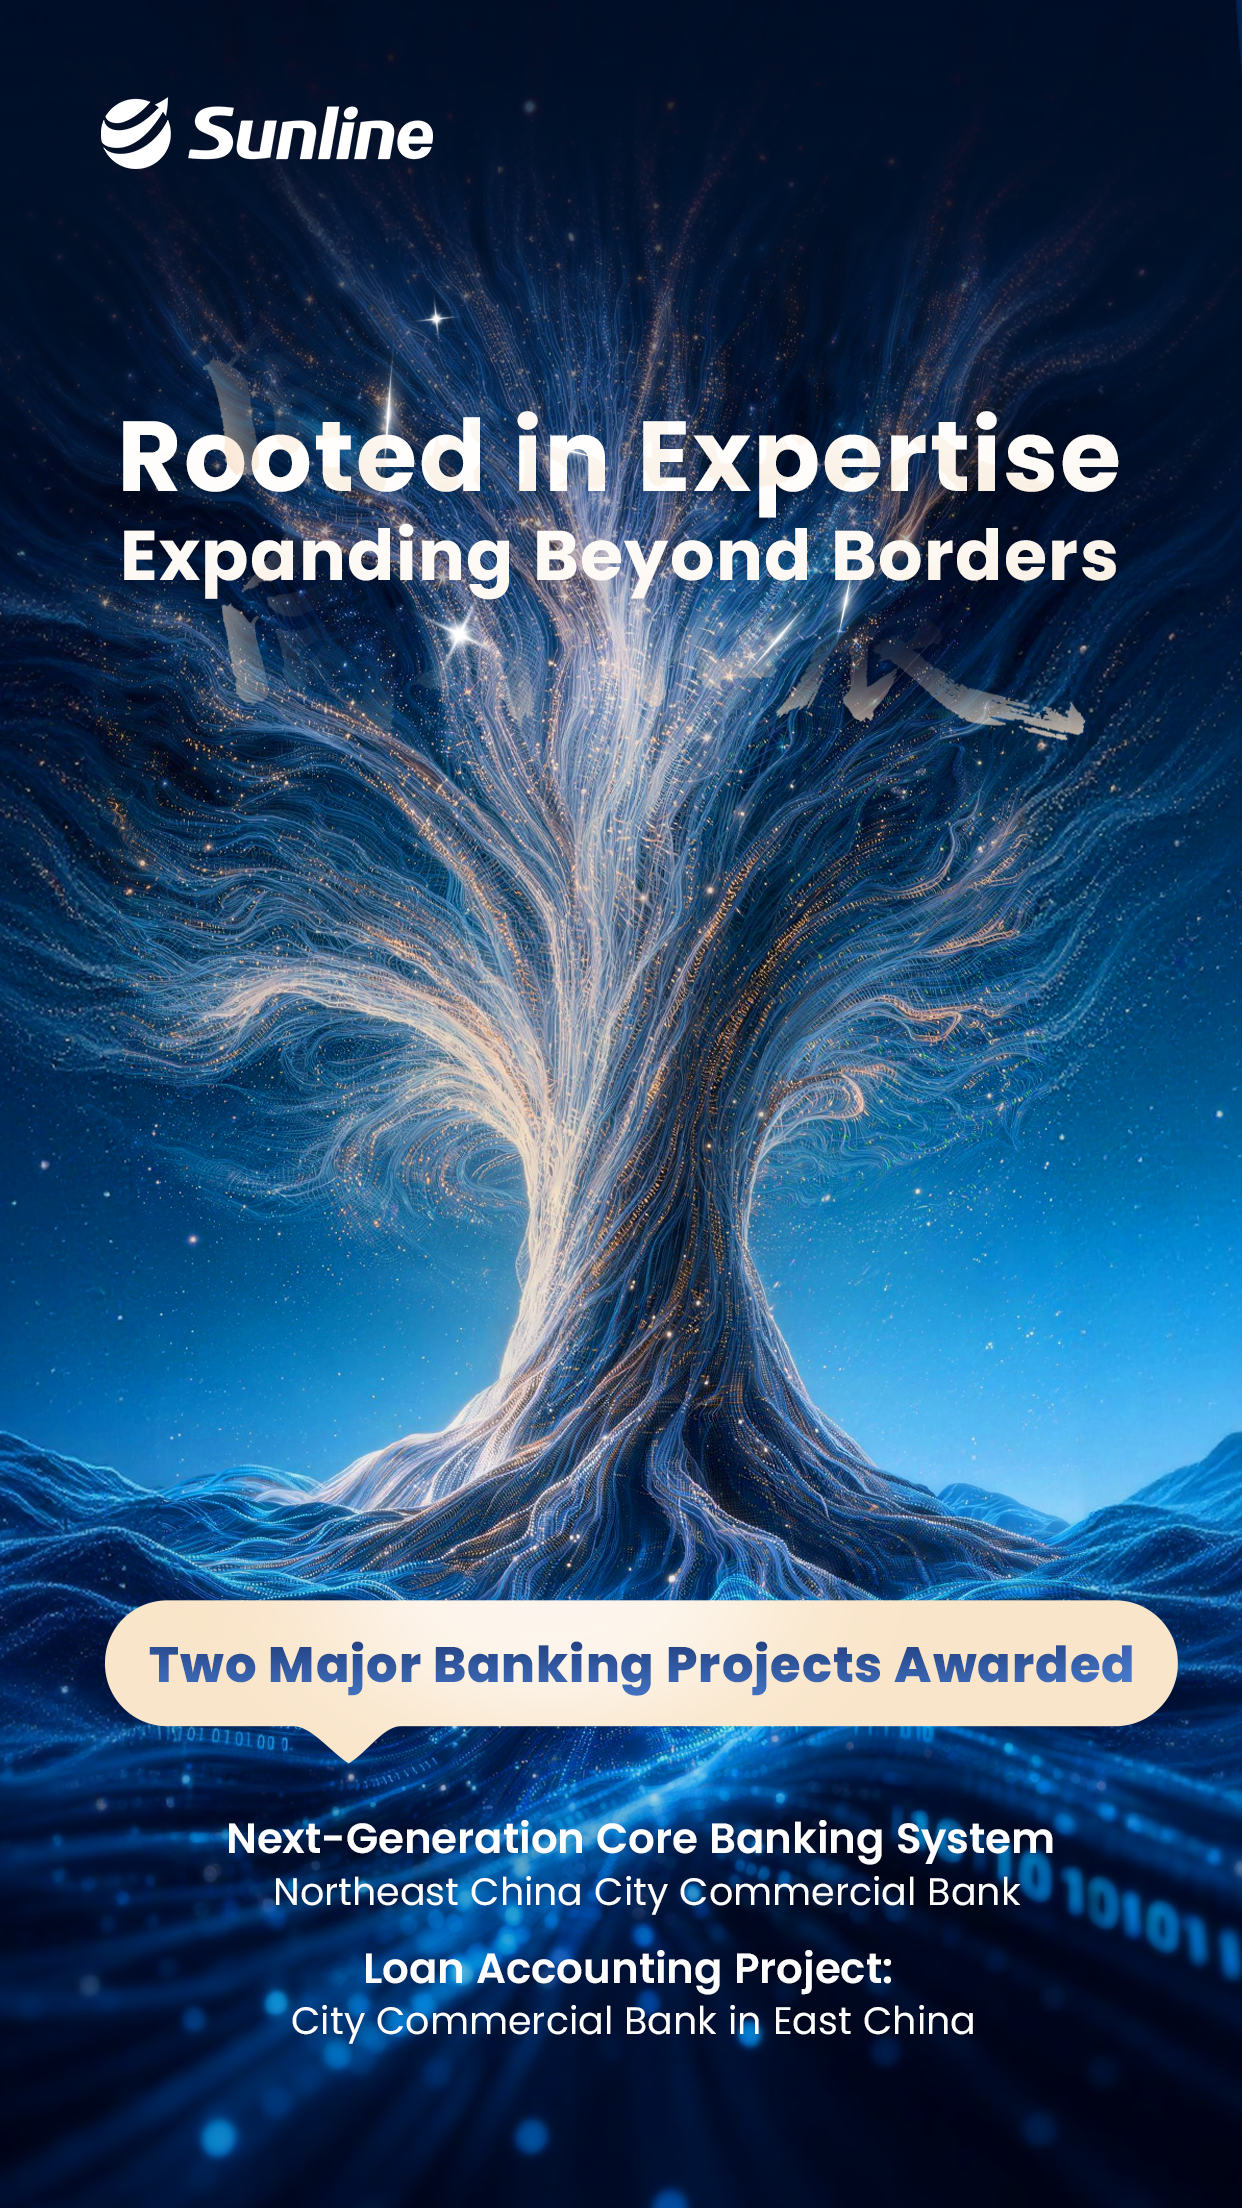
    Demonstrating this architectural shift, Sunline recently secured two core banking modernization projects across Chinese regional commercial banks: a full-scope next-generation core banking system deployment in Northeast China, and a specialized loan accounting platform project in East China.


    Consolidating Full-Scope Core Capabilities

    In the Northeast China deployment, the bank is expanding its technology relationship with Sunline, transitioning from an isolated credit core into a comprehensive, enterprise-grade next-generation core banking platform. While the bank previously operated a dedicated credit engine, its core architecture lacked integrated liability capabilities, such as deposits, payment settlement, and general accounting. 


    The upgraded system unifies these core banking functions while embedding four centralized enterprise capability centers: product, pricing, customer, and shared operations. Designed with horizontally scalable computing nodes, the platform incorporates an active-active disaster recovery architecture spanning two locations and three data centers to deliver continuous 24/7 processing and dynamic failover capabilities during unexpected operational disruptions.


    For regional banks modernizing their core infrastructure, the project reflects a broader shift from function-specific systems towards a unified architecture capable of supporting business growth, operational resilience and continuous product development.


    Specialized Loan Accounting and Architectural Expansion

    The engagement with a city commercial bank in East China represents a vertical capability extension built upon a next-generation core banking system previously implemented by Sunline – currently running stably in production – creating the foundation for a further expansion into loan accounting. 


    The new project represents Sunline’s third loan accounting engagement in the first half of 2026, following projects with a private bank and a provincial rural credit cooperative. The continued adoption across different types of financial institutions provides further evidence of the product’s applicability across varying business and technology environments.


    Engineered with a modular framework and parameterised configuration, this specialized engine manages full-lifecycle credit accounting from origination and servicing through to post-loan workflows without requiring extensive code-level updates. The underlying architecture is designed to support a tenfold growth in account volume over the next decade, ensuring long-term processing efficiency as digital lending scales.


    From Core Replacement to a Broader Banking Platform Strategy

    These dual deployments demonstrate how core banking modernization can evolve beyond a one-off system replacement, reflecting a broader approach to banking technology: building a modular product architecture in which core banking, lending accounting, digital currency and intelligent payments can be deployed independently while working together as part of a broader banking technology stack.


    With more than two decades of experience in financial core business systems, Sunline continues to develop its core solution suite including comprising next-generation core banking, standalone loan accounting engines, digital fiat payment modules, and intelligent transaction processing platforms, providing financial institutions with a scalable, cloud-native foundation designed to sustain enterprise operational resilience and long-term business growth. As financial institutions increasingly combine core modernization with data and AI initiatives, the ability to establish a stable, extensible transaction foundation will remain central to their digital transformation strategies.

  • Sunline Modernizing the Enterprise General Ledger: Transitioning Bank Finance from Post-Event Accounting to Real-Time Intelligence

    Sunline Modernizing the Enterprise General Ledger: Transitioning Bank Finance from Post-Event Accounting to Real-Time Intelligence

    Throughout the first half of 2026, Sunline expanded the deployment of its Enterprise Transaction-Level General Ledger (GL) across state-owned mega-banks, joint-stock commercial banks, regional institutions, and non-bank financial entities. Key operational milestones include a successful single-track production cutover at a major state-owned bank, alongside transaction-level GL go-lives across leading commercial banks. 


    Banking finance transformation is moving beyond regulatory compliance and financial reporting towards real-time accounting, integrated business-finance management and data-driven decision-making. As accounting standards evolve and banks accelerate technology modernization, traditional general ledger platforms are increasingly being challenged by fragmented business and finance data, delayed accounting processes and limited scalability.

    The combination of Sunline’s new project wins and production deployments reflects growing demand for modern GL architectures that can support the scale, regulatory requirements and operational complexity of contemporary banking.

    The Structural Limitations of Legacy General Ledgers

    Traditional general ledger architectures were designed primarily for post-event aggregation and end-of-day reporting. As digital payment channels and high-frequency transactions scale, this legacy model introduces significant operational friction, including fragmented business and accounting data, limited financial visibility, compute bottlenecks under peak load periods, and evolving compliance pressures. 

    Decoupling Transaction Execution from Accounting Logic

    Sunline pioneered the Enterprise Transaction-Level GL to eliminate these constraints by separating transaction execution from accounting rules. Built on a cloud-native, distributed microservices architecture, the platform shifts accounting logic directly to individual transaction events without degrading core banking processing speeds.

    By establishing a unified, bank-wide accounting data center, the platform enforces a single accounting standard across all operational channels. This framework supports both full-scale core modernization for Tier-1 institutions and targeted GL replacement or sovereign technology adoption for regional banks. Furthermore, insights gained from extensive deployment scale continuously inform product iterations-refining automated reconciliations, accounting validation engines, and unified regulatory reporting capabilities. 

    From Accounting Infrastructure to Intelligent Financial Management

    The next stage of GL modernization is increasingly connected to data and AI.

    As transaction-level accounting generates more granular and timely financial data, banks can move beyond retrospective bookkeeping towards automated reconciliation, intelligent accounting validation, integrated regulatory reporting and data-driven financial analysis.

    Sunline is therefore extending its general ledger capabilities towards AI-enabled financial management, with a focus on using accounting data not only for compliance and reporting, but also for analysis, governance and business decision support. The GL is no longer simply where transactions are recorded. It is becoming an important component of the bank’s enterprise data architecture and a foundation for more timely, transparent and intelligent financial management.

    With deployments spanning different types of financial institutions and technology environments, Sunline’s focus is to provide a scalable path from GL modernization and accounting standardization to intelligent financial management, helping banks strengthen their financial technology foundations while preparing for the next stage of digital transformation.

  • Sunline Supports MSCI Hong Kong Forum on Type 11 Readiness and OTC Derivatives Growth

    Sunline Supports MSCI Hong Kong Forum on Type 11 Readiness and OTC Derivatives Growth

    MSCI recently hosted “OTC Derivatives in Hong Kong: From License to Growth” as part of its Investment Risk Summit series, with support from Sunline, MSCI’s exclusive partner for the event. The summit brought together representatives from the Securities and Futures Commission (SFC), securities firms from Hong Kong, mainland China and other markets, professional advisers and technology providers. Discussions focused on the evolving Type 11 licensing regime and the regulatory, operational and commercial considerations facing firms building OTC derivatives businesses in Hong Kong.


    Tom Jenkins, Senior Director, Intermediaries, Securities and Futures Commission, delivered a keynote on supervisory expectations for OTC derivatives. He discussed the framework underpinning the Type 11 regime, the areas supervisors consider as firms prepare for licensing, and the characteristics of a well-structured OTC derivatives operation. Governance, risk management, operational capabilities and internal controls featured prominently in the session.


    For firms preparing for the Type 11 regime, starting early provides more time to assess their licensing, governance and operational readiness, and to identify the capabilities that may need to be strengthened.


    The panel discussion brought together securities practitioners, professional advisers and technology specialists to examine how firms are approaching Type 11 readiness in practice. The discussion covered preparation timelines, capital considerations, implementation priorities and the business implications of Swap Connect for equity derivatives activities, closely reflecting the practical focus set out in MSCI’s programme. Panellists noted that a comprehensive licensing programme may involve more than 40 regulatory documents and that preparation may take approximately eight to 12 months as established implementation approaches continue to develop. This reinforces the importance of starting early and allocating sufficient time and resources. The discussion also highlighted the need for clear ownership and cross-functional coordination. A CEO-led steering structure, supported by a dedicated project management office, can help align work across front-, middle- and back-office functions and coordinate the end-to-end readiness programme.


    Robust data governance is equally important. Firms need consistent, accurate and traceable data to support detailed reporting, risk measurement and day-to-day operations. As Swap Connect and related market access channels continue to develop, Type 11 readiness is increasingly relevant not only to licensing, but also to the ability of Chinese securities firms to expand their cross-border derivatives businesses.


    The discussions reinforced that Type 11 readiness is an enterprise-wide undertaking spanning governance, financial management, risk, operations, data and technology. Firms need to coordinate data governance, risk management, trade reporting and operational capabilities to support the long-term development of their OTC derivatives businesses.


    Sunline will continue to contribute to industry dialogue and draw on its project experience in Hong Kong’s securities and capital markets industry to support financial institutions in strengthening their OTC derivatives capabilities.


    Disclaimer: This article summarises discussions from the event and is provided for general information only. It does not constitute legal, regulatory, investment or other professional advice. Firms should assess the application of any rules or requirements considering their own circumstances and consult legal counsel, professional advisers or relevant authorities where appropriate.

  • Downstream Data Modernization: Sunline Dual-Agent AI Framework Accelerates Lakehouse Pipeline Refactoring

    Downstream Data Modernization: Sunline Dual-Agent AI Framework Accelerates Lakehouse Pipeline Refactoring

    Core banking modernization represents one of the most critical structural transformations a financial institution can undertake. However, upgrading the central transaction engine is only half the battle. Upstream modifications to schema architecture, field structures, and business logic effects across downstream data lakehouses, risk modules, and analytical engines.


    During the strict cutover windows, data engineering teams are tasked with manually refactoring thousands of downstream data processing scripts and conducting exhaustive cross-system data reconciliations. Faced with severely compressed testing timelines, banks are often forced to streamline or shortcut verification steps—introducing hidden data discrepancies that threaten regulatory reporting, analytical accuracy, and operational stability.


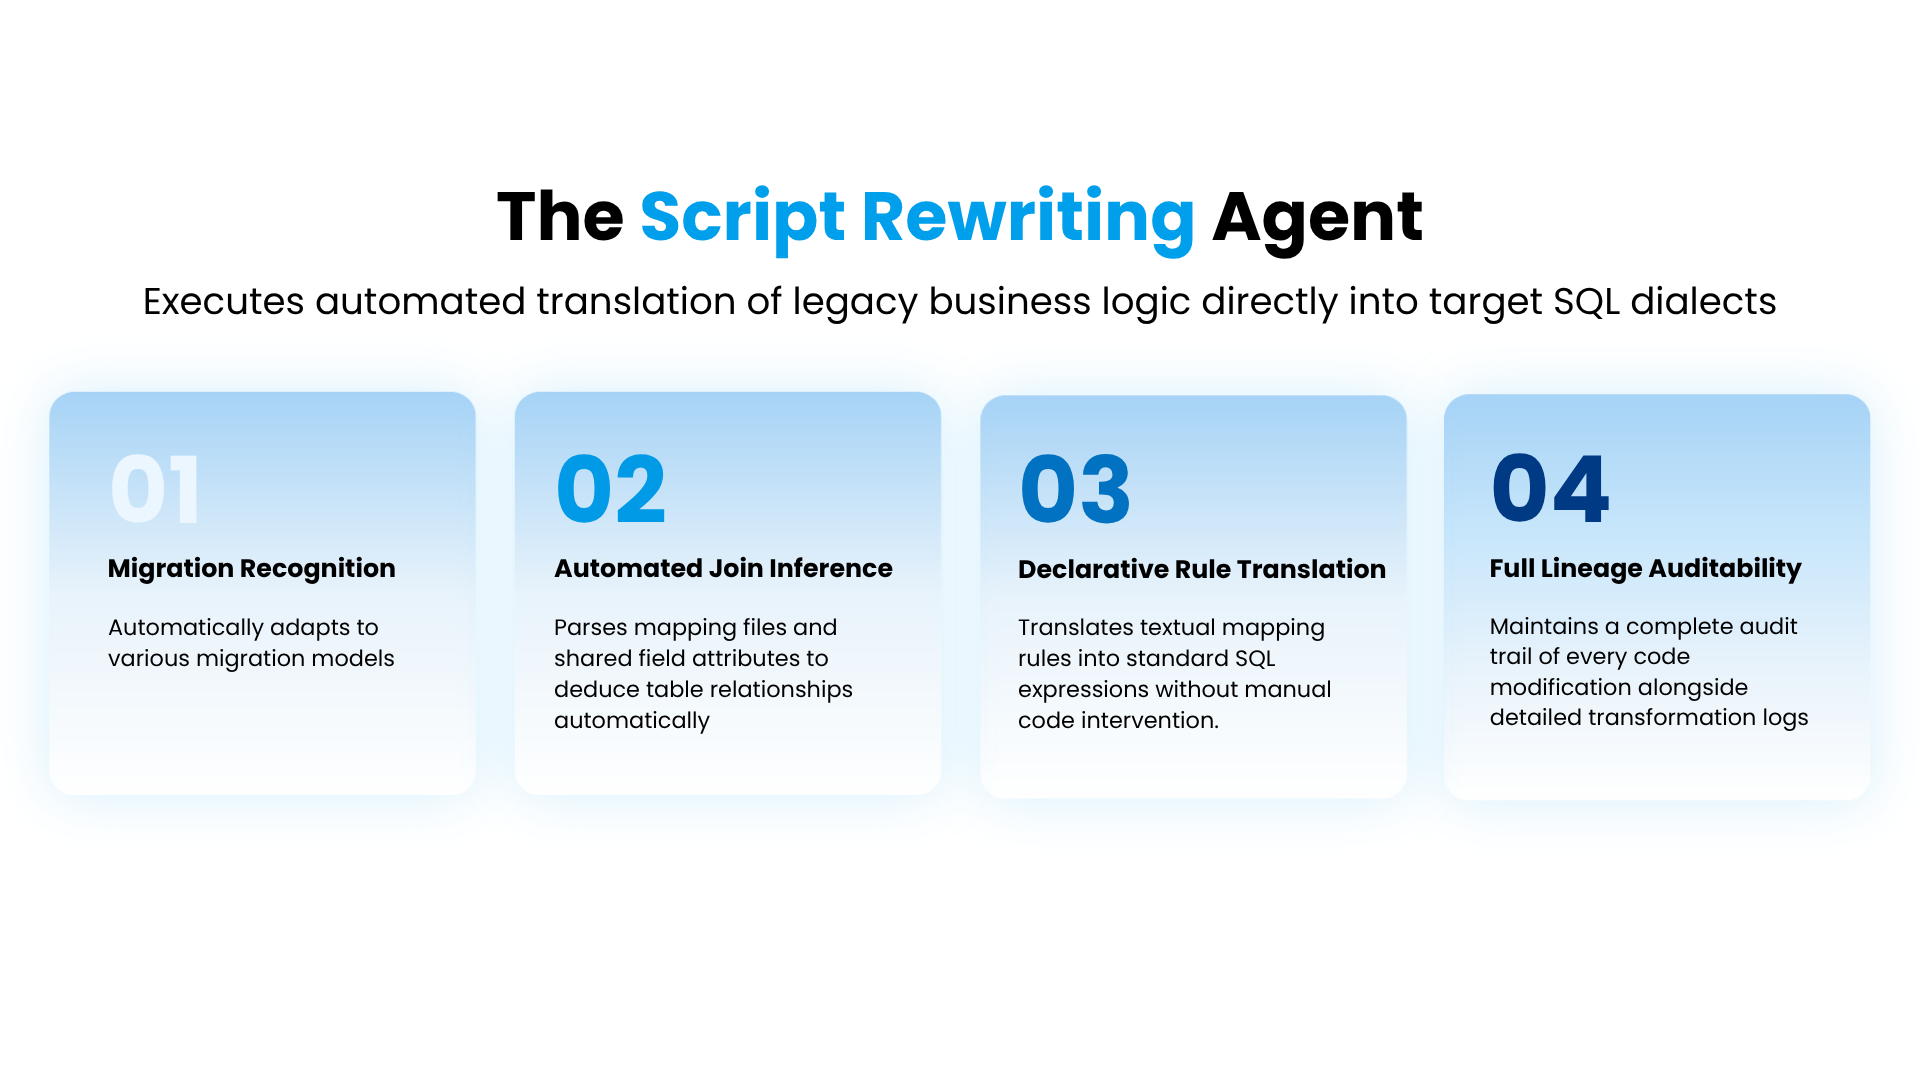
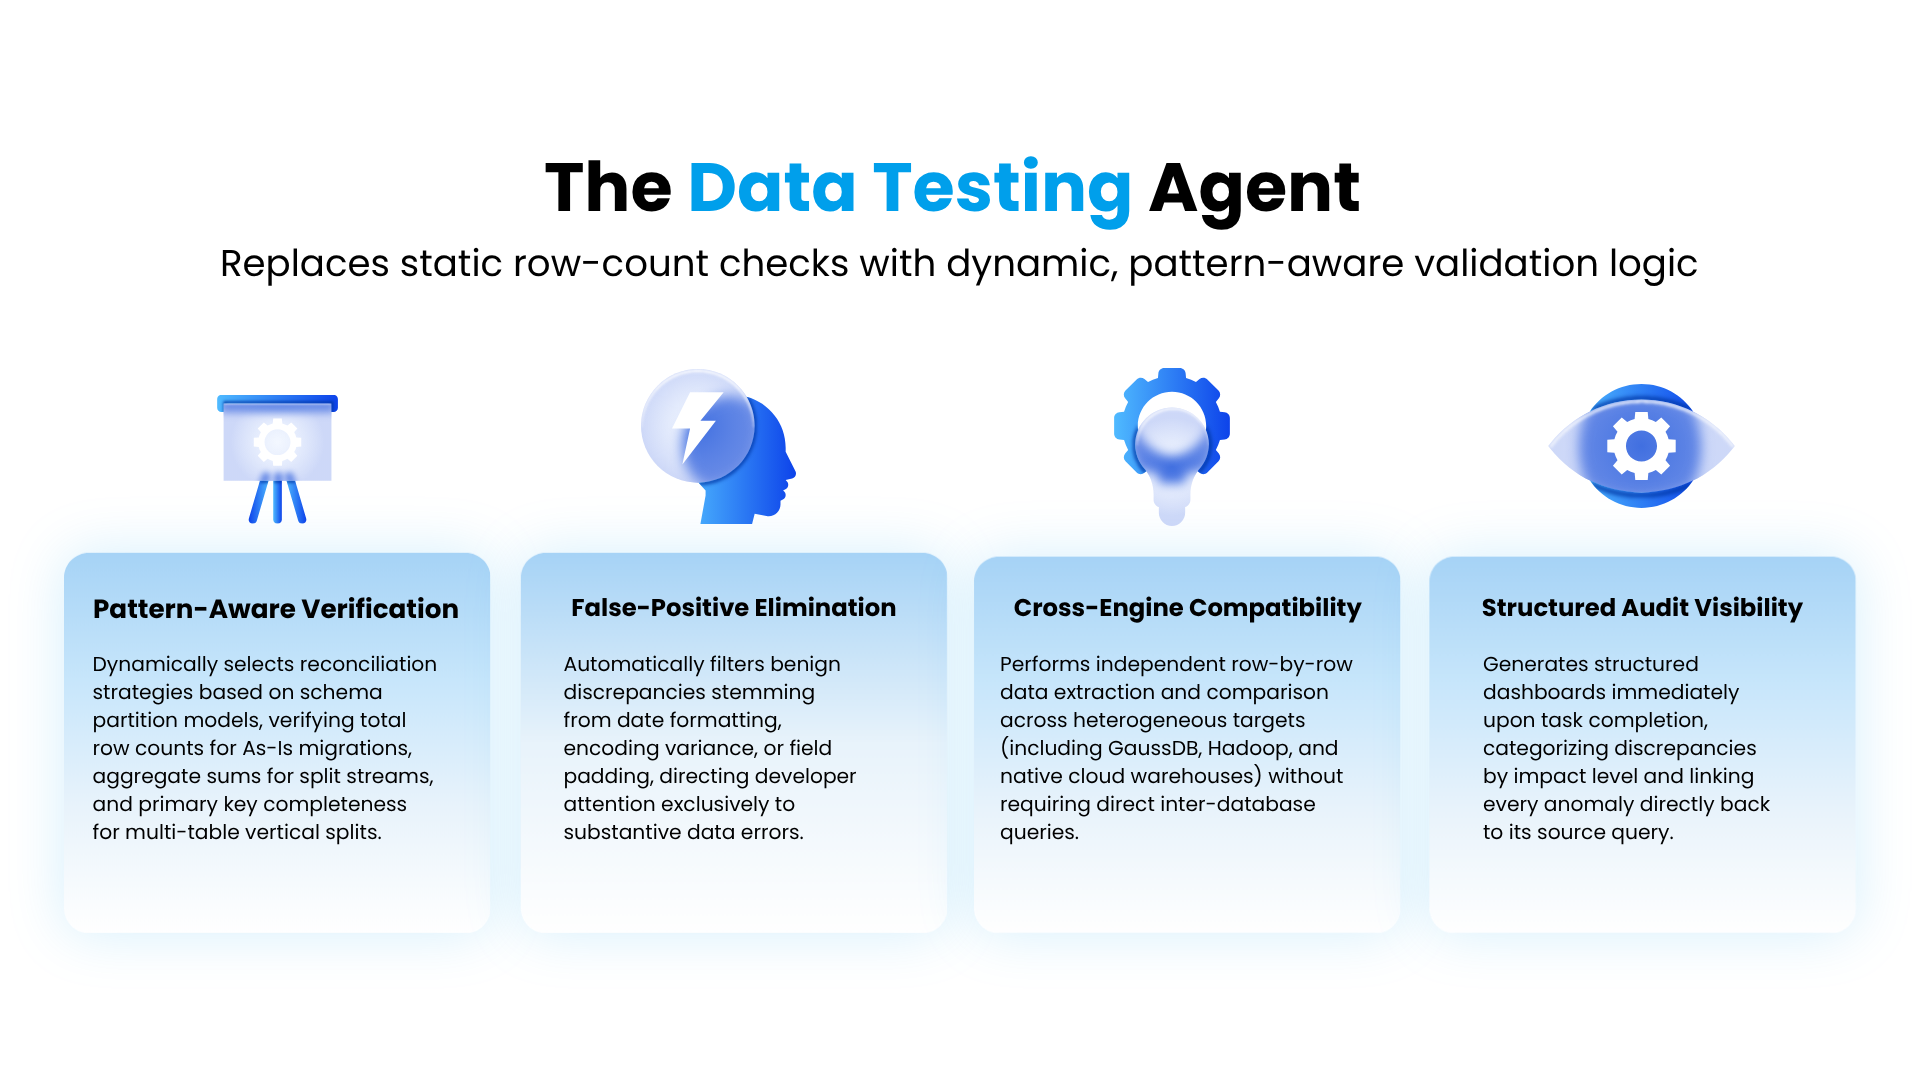
    To eliminate this downstream migration bottleneck, Sunline has introduced its Dual-Agent Collaborative Framework. Driven by a unified Single Source of Truth (SSOT) mapping specification, the multi-agent system automates script refactoring and data validation in a closed loop, accelerating end-to-end lakehouse modernization workflows by 80%.

    Solving Cross-Engine Bottlenecks 

    The framework pairs two specialized autonomous AI agents that operate off a single standardized rule repository, ensuring script conversion logic perfectly matches data validation criteria without human misinterpretation.


    Quantifiable Operational Impact and Governance


    By replacing manual downstream engineering tasks with AI-assisted automation, financial institutions achieve measurable delivery and governance benefits:


    • 80% reduction in overall downstream migration effort: Compresses script refactoring from days to minutes, enables batch processing of hundreds of scripts within hours, and reduces single-table reconciliation from half a day to minutes—shortening overall lakehouse validation cycles from weeks to days.

    • 100% Rule Coverage: Guarantees comprehensive rule application across complex horizontal, vertical, and row-expansion split patterns without omitting secondary field relationships or sub-tables.

    • Unified Governance: Operating off a shared SSOT rule set, the rewriting and testing agents maintain strict consistency between code translation and validation, establishing a complete chain of auditability for regulatory compliance.


    Core banking replacement creates significant operational risk if downstream analytical engines lose synchronization with the central ledger. By combining AI-driven script rewriting with intelligent data validation under a unified governance framework, Sunline’s Dual-Agent Collaborative Framework provides financial institutions with a more controlled, efficient, and auditable approach to downstream data processing—helping reduce migration risk while accelerating core banking transformation.


  • CAICT Executive Interview | Sunline’s Perspectives and Practices in Financial Digital Intelligence

    CAICT Executive Interview | Sunline’s Perspectives and Practices in Financial Digital Intelligence

    As artificial intelligence reshapes the foundations of enterprise software, financial institutions are rethinking how data platforms can support more intelligent, automated and business-oriented operations. In an executive interview with the China Academy of Information and Communications Technology (CAICT) under its Zhuji digital transformation initiative, Yulin Cai, President of Data Business at Sunline, outlines how DataOps is transitioning from static data infrastructure into an autonomous value pipeline.

    The conversation examines how DataMind, Sunline’s self-developed integrated data intelligence platform, combines DataOps, lakehouse architecture and AI to help financial institutions move from AI experimentation towards production-ready applications and measurable business outcomes.

    Q1: As AI changes the way financial institutions use data, how is DataOps evolving from traditional infrastructure into an intelligent value pipeline?

    Yulin Cai: This transformation operates across two complementary dimensions:

    • DataOps as the AI Foundation: DataOps provides the automation methodology required to elevate raw lakehouse storage into trusted, governed data assets. By integrating multi-modal storage, real-time consumption, and enterprise semantic modeling, institutions inject domain business context directly into data pipelines. This contextual foundation bounds AI reasoning, curbing model hallucinations and ensuring regulatory compliance.

    • AI-Driven DataOps Automation: Embedded AI capabilities automate schema design, code generation, testing, maintenance, and data governance. This elevates DataOps from a manual, labor-intensive operational workflow into an agile, self-evolving value pipeline.

    DataOps and AI are mutually reinforcing: DataOps delivers the governed data foundation AI requires, while AI injects automated intelligence back into DataOps – redefining the value boundaries of modern enterprise data platforms.

    Q2: DataMind natively integrates Agent modules into its core platform capabilities. What is the core driving logic behind this architecture, and how is it structured?

    Yulin Cai: The starting point is a practical one: AI needs to be connected to reliable data, domain knowledge and enterprise workflows before it can create sustainable business value.

    DataMind therefore does not treat AI agents as a separate add-on. Agent capabilities are integrated into the platform alongside data engineering, data governance and analytics.


    The architecture combines Base LLM with Domain Knowledge Injection, allowing organizations to build specialized agents for specific financial workflows. Each agent operates within a dedicated sandbox environment, where it can invoke tools, execute tasks and perform self-correction under defined controls.


    This is particularly important in financial services. An enterprise agent cannot simply generate an answer; it needs to operate within appropriate business rules, data boundaries and governance requirements. The combination of DataOps, lakehouse and AI provides the technical foundation for making AI more trustworthy, traceable and operationally controllable.

    Ultimately, the objective is to move AI from isolated experimentation towards integration with real enterprise processes.

    Q3: Enterprise AI deployment faces widespread bottlenecks in model hallucinations, task planning accuracy, and single-agent execution limits. How does Sunline overcome these technical hurdles?

    Yulin Cai: One of the key lessons is that reliable enterprise AI is an engineering problem as much as a model problem.

    Single agents fail when attempting to bridge complex, end-to-end banking processes – such as customer segmentation, strategy design, campaign execution, and performance optimization. To overcome this, DataMind utilizes a Multi-Agent Orchestration Architecture to divide labor among specialized agents collaborating across complete workflows.

    To maintain deterministic reasoning, Sunline embeds two architectural mechanisms refined across 400+ financial institution implementations:

    • Domain Knowledge Guardrails: Encapsulated data models, validation rules, and metric definitions establish a strict business constraint layer that bounds model reasoning and mitigates hallucinations at the source.

    • Standardized Skill Framework: Expert operational workflows are packaged into reusable execution modules (“Skills”), reducing foundational model variability while improving task planning and execution accuracy.

    Q4: Where do you see AI adoption in financial services today? What measurable value can institutions achieve from real-world implementations?

    Yulin Cai: AI has shifted from a passive productivity assistant into an active participant in business operations, where industry focus has moved from foundational model capabilities to deployment efficiency and concrete operational ROI. 

    Our implementation experience shows that this can translate into measurable operational improvements:

    • In data engineering, DataMind uses a multi-agent architecture comprising an orchestration agent, specialist agents covering offline development, real-time development, batch scheduling, data services and intelligent operations, together with an audit agent. This creates an end-to-end workflow from natural-language requirements to automated deliverables and has improved overall data development efficiency by 70%.

    • In data governance, AI is applied across project preparation, rule generation and execution, and reporting. It can identify data quality issues, analyse root causes and recommend remediation actions. In one implementation, rule discovery efficiency improved by 66.7%, while the accuracy of remediation recommendations reached 80%.

    • For business intelligence and data insights, agents can perform tasks such as analysing indicator fluctuations and conducting DuPont analysis, then generate visual reports for management. This has improved indicator interpretation and analysis efficiency by 90%.


    Q5: Expectations for enterprise AI are moving from “efficiency tools” to “decision collaborators.” What strategic milestones must be crossed to transition DataMind from a software platform into an intelligent business partner?

    Yulin Cai: Evolving from a transactional software tool into an enterprise decision partner requires crossing three strategic milestones:

    First, establish a unified semantic command layer between data and AI.

    Financial institutions often have data, metadata, business standards and security policies distributed across different systems. Bringing these elements together into a unified semantic layer can give AI a clearer understanding of enterprise data and business context.


    The longer-term goal is to make DataOps accessible through natural language, allowing business users to express what they need in everyday language while the platform translates those requirements into governed data operations. In other words, natural language becomes a command interface for enterprise data.


    Second, rethink the model for technology delivery.


    Traditional financial technology projects rely heavily on human resources across solution design, architecture, project management and implementation. AI creates an opportunity to redesign this model by introducing AI agents as part of delivery teams, working alongside consultants and engineers while maintaining appropriate technical and business governance.


    Third, industrialize the development and deployment of AI agents.


    Instead of building every agent as a project-specific solution, financial institutions need a more standardized Agent Factory approach. Orchestrated agents can take responsibility for activities such as software development, testing, data migration and quality validation, while human teams focus on architecture, business decisions and higher-value innovation.


    Therefore, DataMind not only aims to become a more intelligent data tool but to evolve into an intelligent business partner – one that brings together trusted data, governed AI and financial domain expertise to help institutions make better use of their data and turn AI capabilities into sustainable business value.

    About CAICT

    The China Academy of Information and Communications Technology (CAICT) is a leading research and advisory institution under China’s Ministry of Industry and Information Technology (MIIT), focusing on information and communications technology, digital transformation and emerging technologies. It plays an important role in technology research, industry development, standards and policy research across China’s digital economy.

  • Core Banking Modernisation in Thailand: Balancing Resilience, Investment Discipline and AI Readiness

    Core Banking Modernisation in Thailand: Balancing Resilience, Investment Discipline and AI Readiness

    At the recent Huawei Thailand Digital & AI Summit 2026 held in Bangkok by Huawei and Thailand’s Ministry of Digital Economy and Society, more than 3,000 government representatives, enterprise customers, telecom operators and ecosystem partners examined how trusted AI, advanced connectivity, computing capabilities and open ecosystems can support Thailand’s digital economy and its ambition to become a leading AI hub in ASEAN.

    For Thailand’s banks, these developments are reshaping both operational priorities and investment decisions. Rising digital transaction volumes are placing greater demands on processing capacity and performance, while expectations of 24/7 access are making system availability and operational continuity business-critical. Meanwhile, subdued loan growth and pressure on profitability are increasing management scrutiny of transformation spending.

    Digital Scale Is Redefining the Economics of Core Modernisation

    Thailand’s banking system already operates at significant digital scale. Within this environment, core banking modernisation extends beyond technology replacement. It is an enterprise transformation intended to strengthen operational resilience, accelerate business change and establish the trusted data foundation required for wider adoption of AI.

    According to the Bank of Thailand’s 2025 Annual Report, PromptPay averaged 74.6 million transfers a day and reached a single-day peak of 96.2 million transactions. At this scale, the operating requirement is twofold: absorbing peak transaction volumes efficiently while keeping essential banking services continuously available. Performance and availability are therefore no longer simply technology measures. They are business-critical determinants of service continuity, customer trust and operational reliability.

    The investment environment is also becoming more demanding. Banking-system loan growth was limited to 0.2% year on year in the first quarter of 2026, while profitability declined as lower lending rates reduced net interest income. Together, these conditions create a dual imperative: sustaining operational resilience while applying greater discipline to transformation spending. Core modernisation is therefore increasingly judged by measurable business value, controlled execution and credible returns, rather than technology renewal alone.

    Drawing on 24 years of experience in banking technology and transformation, Sunline views core modernisation as a management and operating-model decision. The central questions concern where investment will create the greatest value, which business domains to prioritise, how much transition risk the institution is prepared to carry and what evidence will justify further commitment. Effective programmes begin with defined business outcomes and establish clear decision points for migration scope, governance and subsequent investment.

    Turning Banking Priorities into a Controlled Modernisation Path

    No single modernisation path applies to every institution. A bank’s target operating model, priority business outcomes, risk appetite and existing technology investments determine whether the appropriate route involves broad core replacement, migration by business domain, digital-core coexistence or data-first transformation. These considerations also shape the scope, pace and sequencing of change.

    Where phased coexistence is selected as the transition model, Sunline’s multi-core coexistence layer enables banks to modernise in controlled stages rather than migrate all business domains through a single large-scale cutover. SunCBS allows priority domains to move progressively while existing accounts and unmigrated functions remain on the incumbent core. Account location, transaction routing and cross-core processing maintain continuity between the two systems, while reconciliation, monitoring and validation provide control at each stage. This allows banks to verify service continuity, data consistency and operational readiness before expanding the migration scope, helping to contain and reduce migration risk.

    Sunline’s “One Platform, Two Cores” approach connects scalable transaction processing with the bank’s wider data and AI agenda. APStack provides the shared cloud-native technology platform, with SunCBS serving as the transaction core and DataMind as the data core. SunCBS captures trusted business events from daily banking operations, while DataMind transforms this information into governed, reusable data assets that support regulatory reporting, management analytics and real-time data services.

    APStack connects both cores through common integration, API, service orchestration, monitoring and deployment capabilities. This enables transaction processing and data services to operate on a consistent platform rather than as disconnected systems. AIS provides the AI agent orchestration layer, with its current application centred on software engineering productivity through SunTCR. Business-oriented capabilities, including fraud and risk alerts, credit decision support and customer service assistance, form part of DataMind’s future development roadmap.

    Together, these capabilities establish a progression from trusted transaction data and governed information assets to real-time analytics and, over time, AI-assisted decisioning. Banks can strengthen their data foundations as part of core modernisation while maintaining clear governance over how AI capabilities are introduced into banking operations.

    Advancing core modernisation across Thailand’s banking sector requires alignment between banking expertise, enabling technologies and local execution. Sunline will continue to collaborate with Huawei and ecosystem partners to bring these capabilities together. By combining banking-domain and migration expertise with complementary technologies and local delivery capabilities, this ecosystem enables institutions to move from strategic intent to controlled execution, aligning modernisation with business priorities, regulatory obligations and target operating models.

  • Sunline Launches AI-Native SDLC Platform Luban for Governed Core Banking Modernization

    Sunline Launches AI-Native SDLC Platform Luban for Governed Core Banking Modernization

    Core banking modernization remains one of the most complex operational challenges in financial technology. As financial institutions seek to accelerate digital transformation and improve market responsiveness, legacy infrastructure introduces significant engineering friction. 


    Much of a bank’s critical business logic-such as business rules, product configurations, transaction flows, parameter logic, and exception handling remains trapped within legacy codebases and dependent on the tacit understanding of senior engineers. This concentration of tribal knowledge creates key-person risk, elevates the cost of change, and increases operational risk during platform updates. While generic AI coding assistants have improved individual developer velocity, they lack the domain context, end-to-end traceability, and governance required for mission-critical financial infrastructure. 


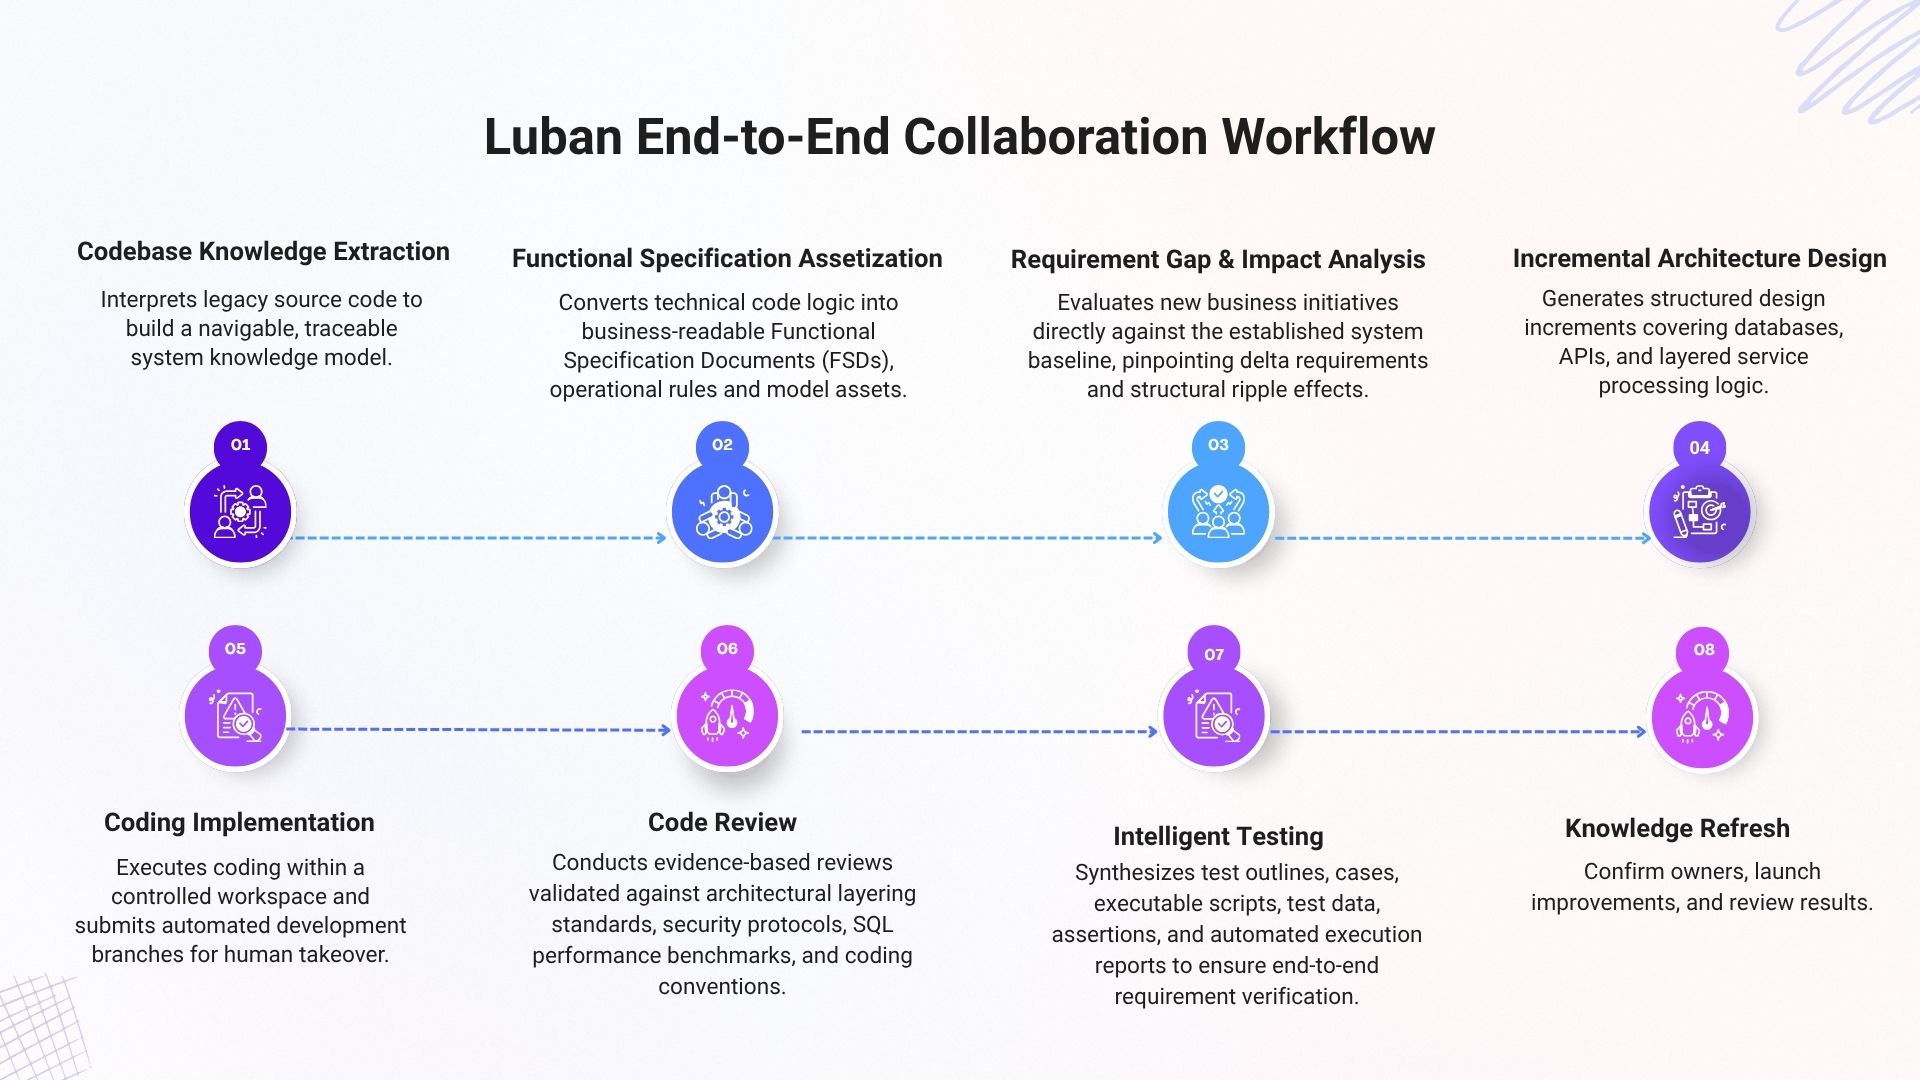
    Addressing this bottleneck, Sunline has introduced Luban, an AI-Native Software Development Life Cycle (SDLC) platform engineered specifically for core banking and enterprise financial systems. Rather than acting as a standalone coding assistant, Luban provides an AI-native engineering workspace across the full SDLC. It coordinates agent-driven execution, human oversight gates, and continuous knowledge institutionalization, helping banks convert dispersed tribal knowledge into standardized, traceable, and reusable engineering assets.


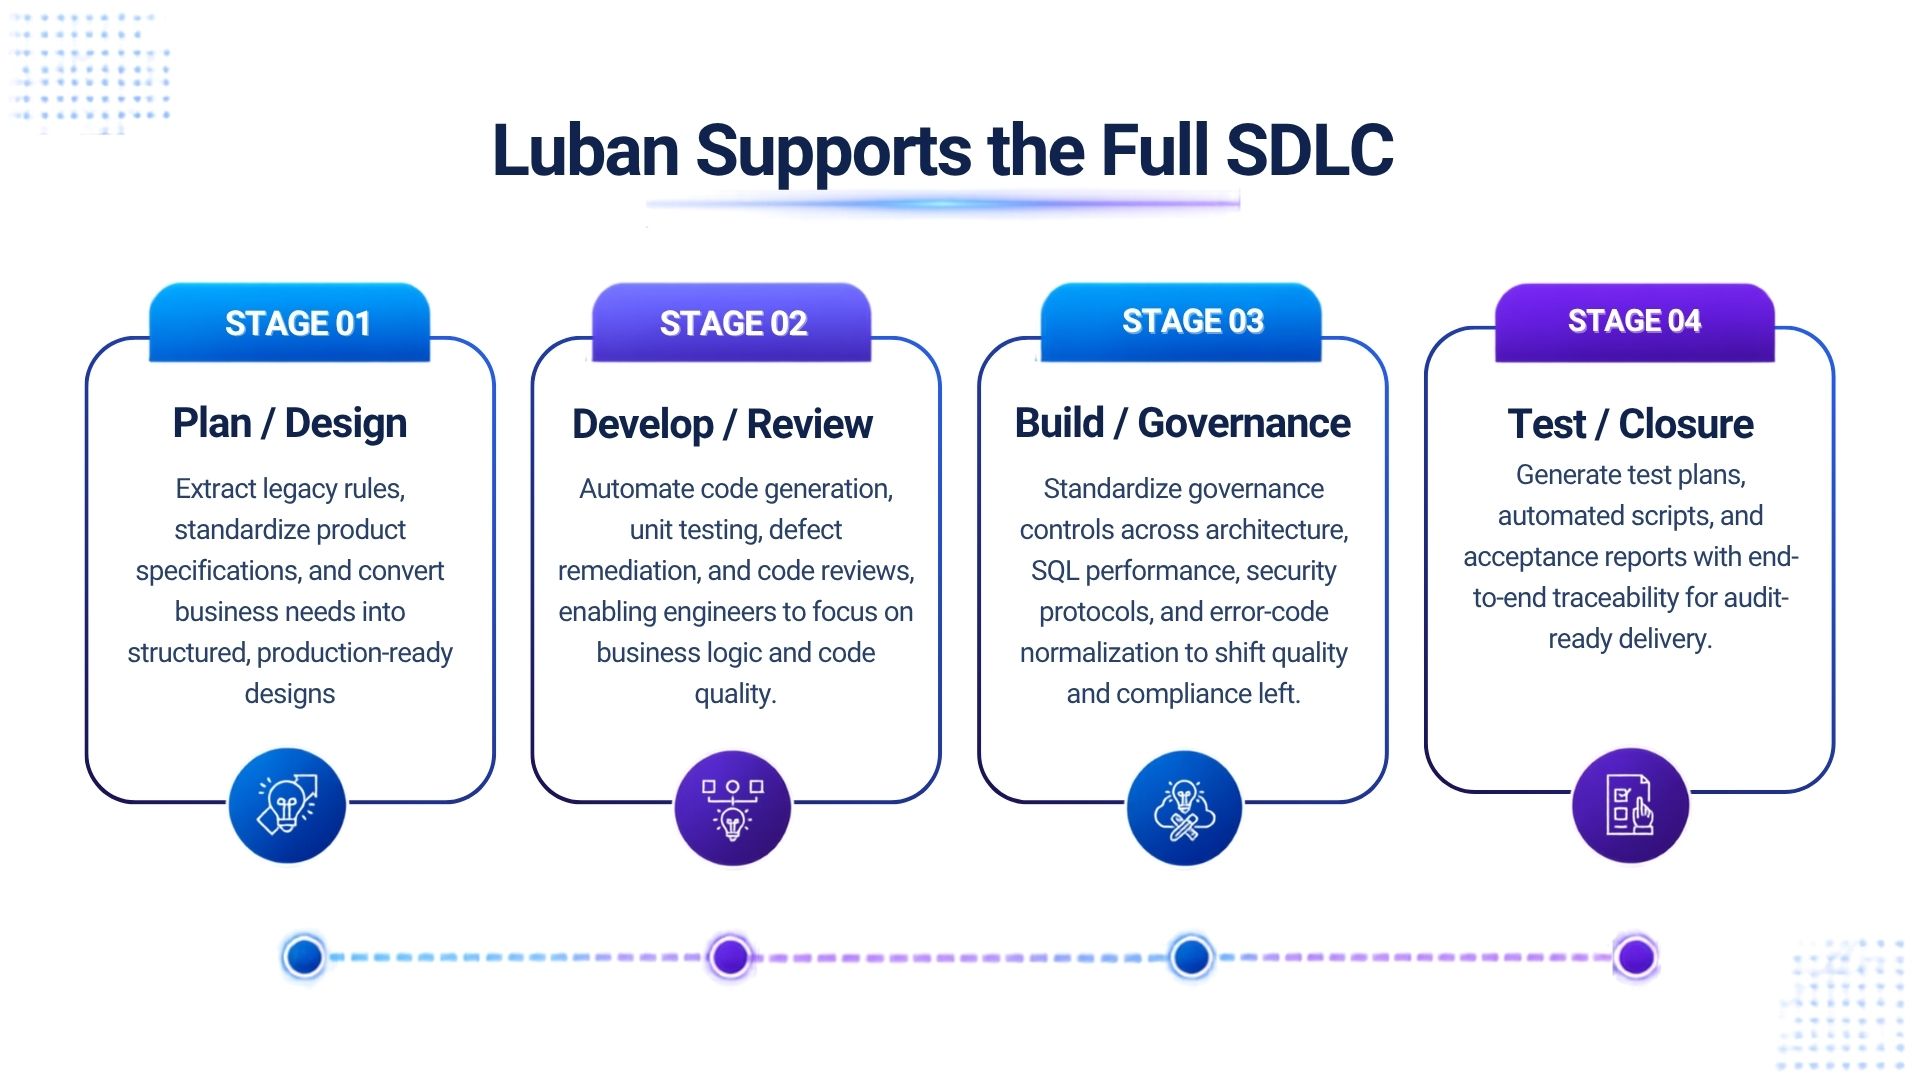
    Implementing Human-Agent Collaborative Operations Across Four SDLC Stages

    Sunline encapsulates two decades of core banking domain expertise, technical standards, and quality governance frameworks into Luban’s reusable agent matrix. The platform embeds human-in-the-loop (HITL) collaboration across the software delivery lifecycle:


    Plan / Design: The platform automatically extracts legacy business rules, standardizes product specifications, and performs requirement elicitation and gap analysis. It formalizes application, database, and API contract designs, converting ambiguous business needs into structured, production-ready delivery assets.

    Develop / Review: Luban automates repetitive engineering tasks including code generation, unit testing, defect remediation, and code review. This allows engineers to focus on validating deliverables, optimizing business logic, and managing code merges, improving both productivity and code quality.

    Build / Governance: Luban standardizes governance controls across architectural layering, SQL performance, resource scheduling, security protocols, and error-code normalization. This shifts quality assurance, security, and regulatory compliance left across the development pipeline.

    Test / Closure: The system generates comprehensive test plans, cases, automated scripts, and acceptance reports. By establishing end-to-end traceability from business requirements to test execution, it ensures deliverables remain fully verifiable and audit-ready.

    From Tribal Knowledge to Institutional Assets

    By connecting requirements, code, configuration and test artefacts, Luban creates a continuously updated knowledge base that can support software analysis and development across the R&D lifecycle, reducing dependence on individual experts while making existing system knowledge more accessible to engineering teams.


    The platform also introduces multi-agent orchestration across activities including AutoBA, AutoTA, AutoDev, and AutoQA. Instead of relying on a single general-purpose AI assistant, specialized agents can perform different tasks within a structured engineering workflow, achieving highly efficient cross-functional collaboration.


    Human oversight remains part of this process. AI execution is constrained by standard operating procedures (SOPs), visual task boards, and mandatory human oversight gates. All design, code, and test artefacts are automatically reconciled and fed back into the central knowledge pool, ensuring continuous institutional learning.


    A Governed, Knowledge-Centric Architecture

    The platform is built on a three-tiered architecture designed to balance automated execution with risk management. Validated in the core deposit account opening transaction scenario, this layered architecture demonstrates the capability to enhance R&D efficiency, while improving traceability and sustainable knowledge reuse. 


    • SunTCR (Taishan Code Reader): The platform reverse-engineers legacy code, configurations, and historical artefacts into a structured, machine-readable institutional knowledge graph, effectively eliminating information silos.

    • AIS Agent Foundation: Acts as the orchestration layer, managing context memory, process orchestration, and agent coordination across complex tasks.

    • Luban Application Layer: Luban encapsulates domain-specific application capabilities and a specialized multi-agent matrix designed for end-to-end software R&D delivery.

    For banks undertaking long-term platform modernization, the ability to preserve institutional knowledge, standardize engineering processes, and establish governed AI workflows can become an important component of technology resilience.


    Luban positions AI-Native SDLC as an engineering model in which knowledge, agents and governance work together across the software lifecycle. For financial institutions, this provides a potential path from developer productivity gains towards a more sustainable engineering capability-one that is less dependent on fragmented expertise and better equipped to manage the complexity of continuously evolving banking platforms.